Walking into a dealership or signing a car financing agreement when you have bad or no credit already feels like a lot. Add unfamiliar words like “APR,” “principal,” and “amortisation” to the mix, and it can feel genuinely overwhelming. But here’s the truth: auto loan terminology explained clearly is not complicated. Once you understand what these terms actually mean, you can read any car loan offer with confidence, spot a bad deal before you sign it, and ask the right car financing questions in Alberta before committing to anything.
Key Takeaways
| Point | Details |
|---|---|
| Understand key terms | Knowing principal, APR, term, and down payment helps you compare auto loans confidently. |
| Longer terms cost more | Long car loan terms lower monthly payments but increase total interest over time. |
| Down payments reduce cost | A larger down payment lowers financed amounts, easing approval and monthly payments. |
| APR shows true cost | APR includes interest and fees, making it the best number to compare car loan offers. |
| Read contracts carefully | Check APR, fees, payment schedules, and prepayment options before signing. |
Breaking down core auto loan terms for Alberta buyers
Every auto loan offer you receive in Alberta will use the same handful of terms. They sound technical, but each one describes something simple. Here is what they actually mean.
- Principal: This is the total amount you borrow. If you buy a car priced at $18,000 and make a $3,000 down payment, your principal is $15,000. Your payments gradually reduce this balance over time.
- Interest: This is what the lender charges you for lending the money. It is calculated as a percentage of the outstanding principal. The higher your rate and the longer you take to repay, the more interest you pay in total.
- APR (Annual Percentage Rate): This is the true cost of borrowing expressed as a yearly percentage, including certain lender fees, not just the interest charge. It is the most reliable number for comparing two different auto loan offers side by side.
- Term length: This is how many months you have to repay the vehicle loan. Common terms run from 36 to 84 months. A shorter term means higher monthly payments but less total interest.
- Down payment: This is money you pay upfront before car financing begins. It directly reduces your principal, which lowers both your monthly payment and the total interest you will pay.
Understanding car loan paperwork in Alberta becomes much easier once these five terms feel familiar. Everything else in a car loan agreement builds on them.
Term length: balancing monthly payment and total cost
Term length is one of the most important decisions in your car loan, and most buyers focus too narrowly on the monthly payment number rather than the full picture.
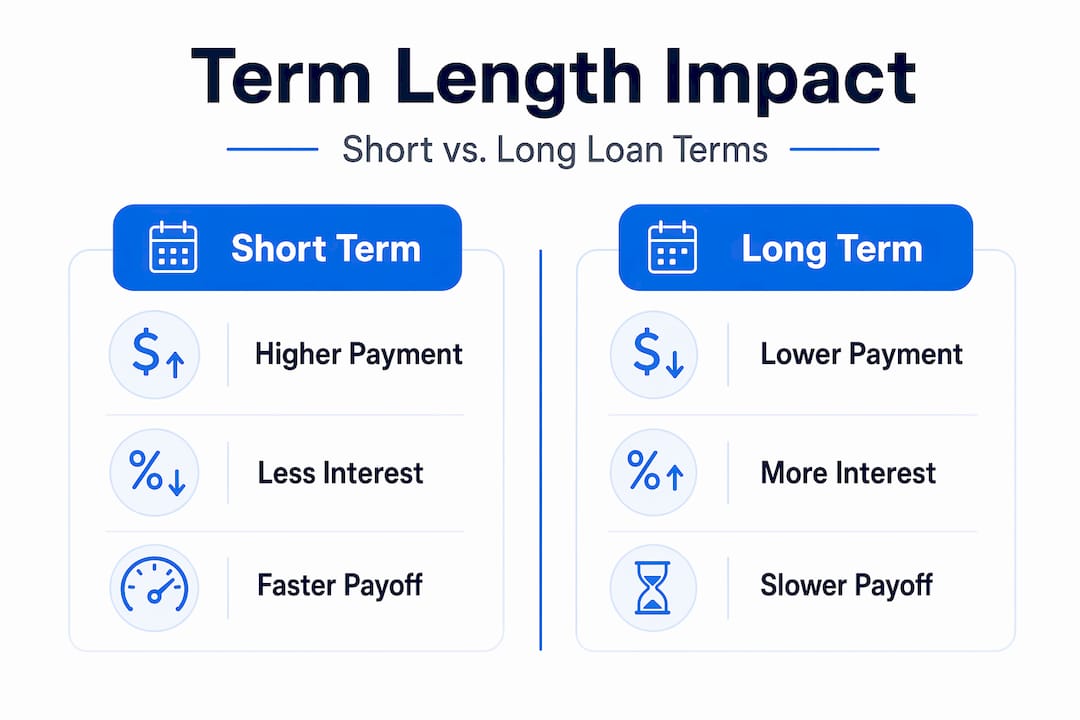
Longer terms lower monthly payments but increase total interest paid over the life of the vehicle loan. A $20,000 auto loan at 9% APR looks very different depending on the term you choose:
| Term | Monthly payment (approx.) | Total interest paid (approx.) |
|---|---|---|
| 36 months | $636 | $2,880 |
| 60 months | $415 | $4,900 |
| 72 months | $356 | $5,632 |
| 84 months | $313 | $6,292 |
The monthly savings from a longer term are real, but you pay for them with significantly more interest over time. This is why understanding the trade-off matters before you commit.
According to average Canadian auto loan data, the average car loan term in Canada is about 68.94 months for new vehicles and 67.68 months for used vehicles as of Q4 2025. Terms of 84 months are increasingly common, driven largely by rising vehicle prices. For buyers rebuilding credit, these longer terms can slow equity buildup, meaning you might owe more than the car is worth for years.
Here is how to think through your term choice:
- Calculate the total interest cost at each term length, not just the monthly payment.
- Check whether the lender allows extra payments without penalty.
- Consider your income stability over the auto loan period.
- Confirm what happens if you want to pay the car loan off early.
Pro Tip: If you can afford even $50 more per month than the minimum payment, applying it directly to your principal can save you hundreds in interest and shorten your repayment timeline considerably.
Review the auto loan requirements in Alberta before locking in a term so you know exactly what to expect from your lender.
How down payments affect your auto loan costs and approval
A down payment does more than reduce what you owe. For buyers with bad or no credit in Alberta, it actively improves your approval chances by lowering the lender’s risk.
Down payments up to 20% are common for car purchases and can improve both approval odds and vehicle loan terms. Even a smaller contribution of $1,000 to $2,000 signals financial commitment and reduces the financed amount meaningfully.
Here is why down payments matter for your situation specifically:
- A lower financed amount means smaller monthly payments, which makes approval more realistic on a tighter income.
- Less money borrowed means less interest charged over the auto loan’s life.
- Lenders see a down payment as a sign of seriousness, which can work in your favour when your credit history is thin or damaged.
- Getting into positive equity faster protects you if you ever need to sell or trade the vehicle before the car or truck loan ends.
Pro Tip: Even trading in your current vehicle counts as a down payment. A trade-in worth $3,500 applied to your next loan is functionally identical to cash down, and many Alberta lenders will accept it without question.
Check out what vehicle loan eligibility information looks like in practice so you can walk in prepared.
Interest versus APR: what Alberta buyers must know
These two numbers appear on every auto loan offer, and confusing them is one of the most common and costly mistakes buyers make.
Interest is simply the cost charged on your principal. APR takes that interest rate and adds certain lender fees, giving you a fuller picture of what borrowing actually costs. As a rule:
“APR is the best number to use when comparing auto loan offers because it reflects the true cost of borrowing, not just the interest charge. It is the only metric that gives you an honest apples-to-apples comparison.” (auto loan terms explained)
In practice, a lender might advertise a 7.9% interest rate. But once administration fees and required add-ons are included, the true borrowing costs reflected in the APR could be 9.2% or higher. That difference matters across a 60 to 72 month car loan.
Key points to remember:
- Always ask for the APR in writing, not just the interest rate.
- If two lenders quote different interest rates but similar APRs, their total costs may actually be comparable.
- A lower interest rate with high fees can cost more than a slightly higher rate with no fees.
- Alberta buyers with bad or no credit should compare bad credit vs no credit auto loans using APR for a fair side-by-side view.
How your monthly payments are calculated and what affects them
Your monthly payment is not a mystery number. It comes directly from three inputs: the amount financed, the APR, and the term length. Small changes in any one of these three variables can move your payment noticeably.
Here is how each factor plays its role:
- Amount financed: Lower this with a bigger down payment or a less expensive vehicle, and your payment drops immediately.
- APR: Even a 2% difference in APR on a $15,000 car loan over 60 months changes your monthly payment by roughly $15 to $20 and adds up to several hundred dollars over the full term.
- Term length: Spreading the same amount over more months lowers each payment but raises total interest, as shown in the earlier table.
| Change made | Effect on monthly payment | Effect on total cost |
|---|---|---|
| Larger down payment | Decreases | Decreases |
| Higher APR | Increases | Increases significantly |
| Longer term | Decreases | Increases |
| Extra payments | No change | Decreases |
The mistake many buyers make is focusing only on monthly payment. A dealership can always lower your payment by stretching your term. That does not mean the car loan is more affordable. It means it costs more in the long run. Explore flexible auto financing options in Alberta if you want solutions that balance both.
Reading your auto loan contract: what Alberta buyers should check
Signing without reading is how avoidable surprises happen. Your auto loan contract terms in Alberta should be reviewed carefully before you put pen to paper.
Here is what to look for specifically:
- APR clearly stated: Confirm the APR is listed as a number, not just a general range.
- Non-interest fees: Administration fees, car or truck financing fees, and any mandatory insurance products increase your real cost. These should be itemised.
- Full payment schedule: You should be able to see every payment amount, the date it is due, and how much goes toward principal versus interest each month.
- Prepayment terms: Can you make extra payments? Will they reduce the principal directly? Are there penalties for paying off early?
- Total cost of borrowing: Some contracts show this as a single number. It should match your own calculations based on APR and term.
Pro Tip: Ask the finance manager to walk through the contract line by line before signing. Any lender who refuses or rushes this step is not the right partner for your financing.
Reviewing your auto loan eligibility tips in Alberta beforehand gives you the context to ask sharper questions when the contract is in front of you.
Our perspective: why knowing the language protects you more than a good credit score
Here is something most car or truck financing articles will not tell you. Knowing auto loan terminology well protects you more reliably than having a good credit score.
A buyer with strong credit who does not understand APR can still get trapped in an 84-month vehicle loan loaded with fees. A buyer with bad credit who understands exactly what they are signing can negotiate meaningfully, spot unfair terms, and build a vehicle loan structure that actually works for their life.
We have worked with thousands of Alberta residents who came in believing their credit situation left them with no options and no power. The ones who asked clear questions, understood the difference between interest and APR, and knew how their term length affected total cost consistently ended up with better outcomes than those who simply hoped for the best.
The terminology is not there to confuse you. But it does separate buyers who accept whatever they are offered from buyers who negotiate from an informed position. The information in this guide is not complicated once it is laid out plainly. Use it.
Get approved with Summit Auto Loans today
At Summit Auto Loans, we believe you deserve to understand exactly what you are agreeing to. Whether your credit is damaged, thin, or non-existent, our team walks you through every term in plain language before you sign anything. We work with Alberta residents across all credit situations and get you pre-approved in seconds without the judgement. Our specialists will explain your APR, your payment schedule, and your options clearly, so there are no surprises on signing day. If you are ready to move forward, apply for auto financing today and let us find a vehicle and auto loan structure that genuinely fits your situation.
Frequently asked questions
What does APR include besides interest in an auto loan?
APR includes certain lender fees beyond the basic interest charge, making it a more accurate cost comparison than the interest rate alone.
Is a longer auto loan term better if it lowers my monthly payment?
A longer term does lower monthly payments, but total interest paid increases significantly, often making the auto loan more expensive overall.
Why does making a larger down payment help if I have bad or no credit?
A larger down payment reduces the financed amount, and down payments improve approval odds by lowering lender risk while reducing your monthly payment and total auto loan cost.
How can I avoid surprises when signing my auto loan contract?
Review the APR, all fees, the full payment schedule, and prepayment terms carefully before signing to understand what you are actually agreeing to.
Can I reduce the interest I pay over the life of my auto loan?
Yes. Choosing a shorter term and making extra principal payments early can both reduce interest, since extra early payments reduce total interest more effectively than later payments due to how interest is front-loaded.