Many Canadians believe that a poor credit history means they simply cannot get a car loan. That assumption stops a lot of people from even trying. The bad credit car loans definition is actually straightforward: these are specialised auto financing products built for borrowers whose credit history has negative marks, giving them access to vehicle financing that standard lenders typically decline. At Summit Auto Loans, we see this confusion every day, and this article breaks down exactly what these loans are, how they work, what to watch out for, and how you can improve your chances of getting approved.
What defines a bad credit car loan
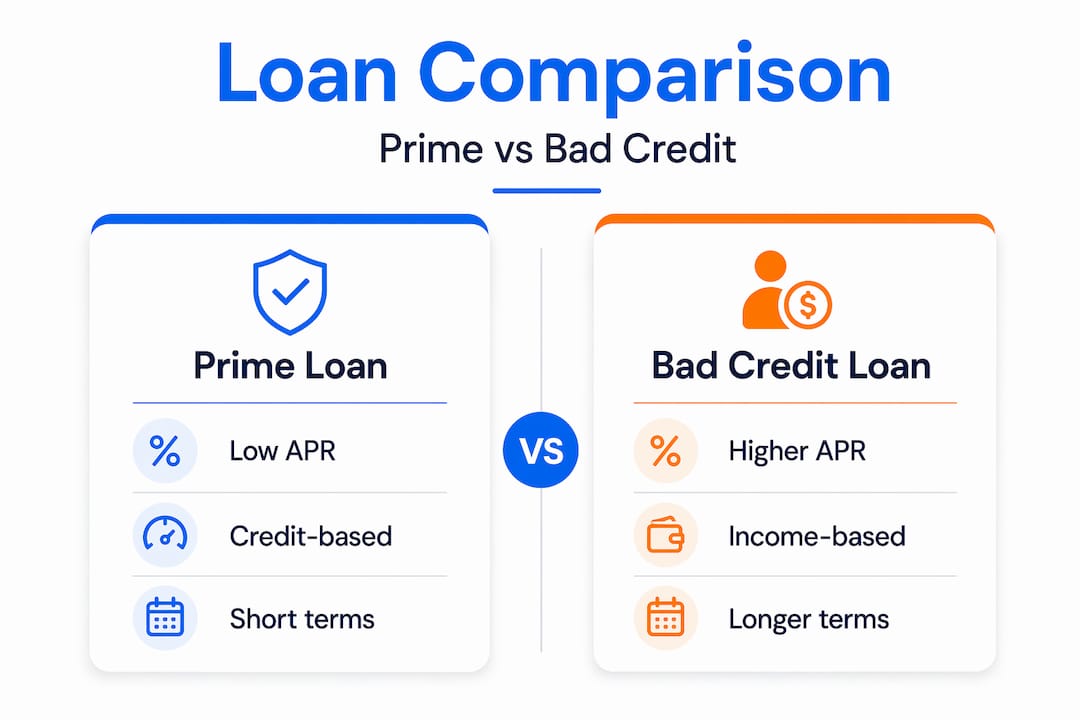
A bad credit car loan is a auto financing product designed specifically for people whose credit history falls into the subprime category. The definition of subprime auto loans covers borrowers with significant negative marks on their credit file, such as missed payments, collections, or prior defaults. These subprime auto loans exist because lenders recognise that credit history alone does not tell the whole story of a borrower’s ability to repay.
What separates bad credit auto financing from conventional loans is the approval criteria. Rather than relying solely on your credit file, lenders look at your income and debt-to-income ratio as major qualifying factors. Someone with a troubled credit past but a steady paycheque and manageable existing debts is a much stronger candidate than their credit file alone might suggest.
It is also worth understanding that subprime status reflects credit defaults, not your income level, and it is a temporary condition that changes with responsible financial habits.
| Feature | Prime borrower | Subprime borrower |
|---|---|---|
| Credit history | Clean, consistent payments | Negative marks, defaults |
| Primary approval factor | Credit profile | Income and debt ratio |
| Typical terms | Shorter, standard | Longer, more flexible |
| Down payment expectation | Low to none | Moderate recommended |
| Auto loan availability | Broad | Specialised lenders |
Pro Tip: Even if your credit file looks rough, showing a stable monthly income and keeping your existing debts manageable gives lenders concrete reasons to approve you.
Common features of bad credit auto financing
When you explore bad credit auto financing options, you will find that the structure of these differs from prime loans in a few meaningful ways. Understanding those differences upfront prevents surprises later.
Here are the key features and considerations to know before you apply:
- Flexible auto loan terms. Auto loan terms exceeding 72 months are increasingly common as lenders try to keep monthly payments at a level borrowers can realistically manage.
- Income verification is central. Many lenders working with bad credit borrowers look for a minimum monthly income around $2,500 and a debt-to-income ratio that stays within manageable limits.
- Down payments strengthen your application. Even a modest down payment signals financial commitment and reduces the lender’s exposure.
- Vehicle selection may be guided. Some lenders work with specific vehicle age and value ranges to limit their risk.
- Responsible repayment rebuilds credit. On-time payments on a bad credit auto loan actively improve your credit profile over time.
What surprises many borrowers is that these car loans, when managed well, can serve as a genuine credit-rebuilding tool. Review the best practices for auto loans in Canada to understand how to position yourself effectively from the start.
Pro Tip: Before applying, add up all your current monthly debt obligations and compare them to your monthly income. If your debts already consume more than half your income, focus on reducing one or two balances first. It makes a measurable difference to lenders.
Risks and misconceptions to understand
The biggest myth about bad credit car loans is that they are predatory by default. That is not accurate. Licensed lenders who specialise in subprime auto financing operate within regulated frameworks, and there are many myths about bad credit car loans worth clearing up before you make any decisions.
The real risk area to avoid is no-credit-check loans and car title loans. These are fundamentally different products. Car title loans average 300% APR, which is an extraordinary cost compared to standard bad credit auto financing. They also require you to pledge your vehicle as collateral, meaning a single missed payment can result in repossession.
| Car loan type | Key feature | Cost level | Risk level |
|---|---|---|---|
| Bad credit auto loan | Income-based approval | Moderate | Moderate, managed |
| No-credit-check car loan | No financial vetting | Very high | Very high |
| Car title loan | Vehicle as collateral | ~300% APR average | Severe, repo risk |
The second significant risk with legitimate bad credit loans is negative equity. Borrowers with auto loans over 72 months risk staying financially underwater on their vehicle for a longer period, meaning they owe more than the car is worth. This matters most when you want to trade in or sell the vehicle before the vehicle loan is paid off.
Understanding the impact of bad credit on car financing means knowing both the doors it opens and the traps to avoid. An informed borrower is a protected borrower.
How to prepare for bad credit loan approval
Getting approved is not just about showing up with a request. A little preparation makes the process faster and your application stronger. The steps below are practical and straightforward.
- Set a realistic monthly budget. Calculate what you can comfortably afford each month after rent, groceries, utilities, and existing debts. Be honest. Overcommitting leads to missed payments, which deepens the credit problem you are trying to solve.
- Document your income clearly. Recent pay stubs, bank statements, or proof of consistent deposits give lenders the confidence they need. Stable income is one of the most powerful factors in your favour.
- Calculate your debt-to-income ratio. Add all monthly debt payments and divide by your gross monthly income. Lenders typically look for this to sit below 50%, per typical lender benchmarks.
- Save for a down payment if possible. Even a small amount reduces the size and signals financial responsibility.
- Gather your identification and employment details. Having everything ready speeds up the process significantly.
- Be consistent and transparent. Lenders working with bad credit borrowers are not looking for perfection. They want to see that your current financial situation is stable. Accurate information builds trust from the first application.
Review auto financing tips to further understand what lenders in Canada look for and how to present yourself in the best light.
Working with Summit Auto Loans
Summit Auto Loans is built specifically for Canadians who have been turned away elsewhere. The approach is straightforward: your current financial stability matters more than your credit past. That philosophy is reflected in a pre-approval process that takes seconds, not days, and a team that treats every application with respect rather than judgement.
Flexible auto loan terms mean your monthly payment is structured around what you can actually afford. The process is transparent from start to finish, with no hidden requirements and no unnecessary complications. For borrowers who are also trying to rebuild their credit standing, responsible repayment through Summit Auto Loans creates a track record that opens more financial doors over time.
Pro Tip: When you apply with Summit Auto Loans, have your most recent proof of income and a clear picture of your monthly expenses ready. The more clearly you can show financial stability, the faster and smoother your approval process will be.
My take on bad credit car loans
I have spent years watching people talk themselves out of applying for vehicle financing because they assume their credit history disqualifies them automatically. That assumption costs people real transportation options, and often real employment opportunities tied to having a reliable vehicle.
What I have learned is that the most important question a lender asks is not “what happened in the past?” It is “can this person reliably make payments right now?” A stable job, a manageable debt load, and a straightforward application often matter far more than a difficult credit chapter. The risk assessment lenders use is more nuanced than most people expect.
I also think people underestimate how much of a long-term trap extended terms can be. A 96-month car loan might look attractive on a monthly payment basis, but borrowers frequently underestimate the negative equity risks that come with being locked into a depreciating asset for eight years. My advice: take the longer term if you need it, but pay ahead when you can.
The right lender does not make you feel like a risk. They make you feel like a client.
Ready to move forward with Summit Auto Loans?
If this article has helped clarify what bad credit car loans are and how they work, the next step is putting that knowledge into action. Summit Auto Loans works with Albertans across all credit backgrounds, offering flexible terms, a quick pre-approval process, and a team that genuinely wants to see you in the right vehicle. There is no pressure and no judgement. You can get approved today in a matter of minutes, or use the loan payment calculator to explore what your monthly payments might look like before you commit to anything. Reliable transportation is within reach, and Summitautoloans is here to help you get there.
FAQ
What are bad credit car loans?
Bad credit car loans are specialised auto financing products for borrowers with negative credit histories. They use income, employment, and debt levels as primary approval factors rather than relying solely on credit history.
What are the requirements for bad credit car loans?
Most lenders look for a stable monthly income (often around $2,500 or more), a debt-to-income ratio under 50%, valid identification, and proof of employment or consistent income deposits.
How does bad credit affect car financing?
Bad credit limits access to standard auto financing products and typically results in longer terms to keep payments manageable. It does not eliminate options, but it shifts approval criteria toward income and financial stability.
Can a bad credit car loan help rebuild my credit?
Yes. Making consistent, on-time payments on a bad credit auto loan builds a positive payment history, which is one of the most effective ways to improve your credit profile over time.