If you have a damaged credit history, you have likely heard that a credit rebuilding car loan can help you get back on track financially. That is true. But the version most people imagine — where a single loan magically repairs years of credit damage in a few months — is not how it actually works. Understanding what a credit rebuilding car loan is, how it functions, and what it demands from you as a borrower is the difference between using this tool wisely and making your situation harder. This guide covers all of it, from how the loan works to practical credit rebuilding car loan steps you can take right now.
What is a credit rebuilding car loan?
A credit rebuilding car loan is an auto financing product designed specifically for borrowers with damaged, limited, or no credit history. Unlike a standard auto loan that typically requires strong credit to qualify, these are structured to give credit-challenged Canadians access to vehicle financing while simultaneously creating an opportunity to rebuild their credit standing.
The core mechanic is straightforward. When you make payments on your car loan, your lender reports those payments to Canada’s credit bureaus. Every on-time payment adds a positive record to your credit file. Over time, that consistent positive history is what actually improves your credit profile. The car loan does not fix your credit. Your behaviour with the auto loan does.
Here is what typically distinguishes a credit rebuilding auto loan from a conventional one:
- Payment reporting: Your lender reports your payment activity to credit bureaus monthly, which directly influences your credit file.
- Accessible approval criteria: Lenders like Summit Auto Loans assess your full financial picture, not just a single credit metric.
- Structured terms: Auto loan terms are designed to be manageable, giving you a realistic path to consistent payments.
- Long-term focus: The goal is sustained financial improvement, not a short-term patch.
Pro Tip: Look for lenders that offer financial guidance alongside your auto loan. Some lenders provide coaching and incentives like payment rewards to keep you motivated and on track.
How an auto loan rebuilds your credit over time
The connection between your auto loan and your credit profile is more direct than most people realise. Payment history accounts for 35% of your credit score calculation. That makes it the single biggest factor in your credit recovery. Every month you pay on time, you are actively rebuilding that foundation.
Beyond payment history, a car loan adds an instalment account to your credit mix. Credit bureaus favour borrowers who can responsibly manage different types of credit. Having an active instalment loan alongside any revolving credit you carry (like a credit card) demonstrates broader creditworthiness.
What does a realistic timeline look like? Most borrowers who stay consistent see meaningful score recovery within 12 to 24 months of maintaining on-time payments after a negative credit event. That is not fast, but it is real progress.
There are a few traps to avoid:
- Focusing only on the monthly payment. A lower monthly payment often means a longer term, and longer terms increase your total cost significantly. Always calculate the full amount you will pay over the life of the car loan.
- Expecting early payoff to accelerate your score. It will not. Paying off a car loan early does not speed up credit recovery. Consistent, long-term payment history is what moves the needle.
- Missing even one payment. A single missed payment can erase months of progress. Treat each payment date as non-negotiable.
“Credit recovery is not a sprint. It is a disciplined, month-by-month commitment to doing the small things right, consistently.”
Steps to take before and during your car loan
Preparation matters enormously. The borrowers who get the most out of a credit rebuilding auto loan are the ones who set themselves up well before they even apply.
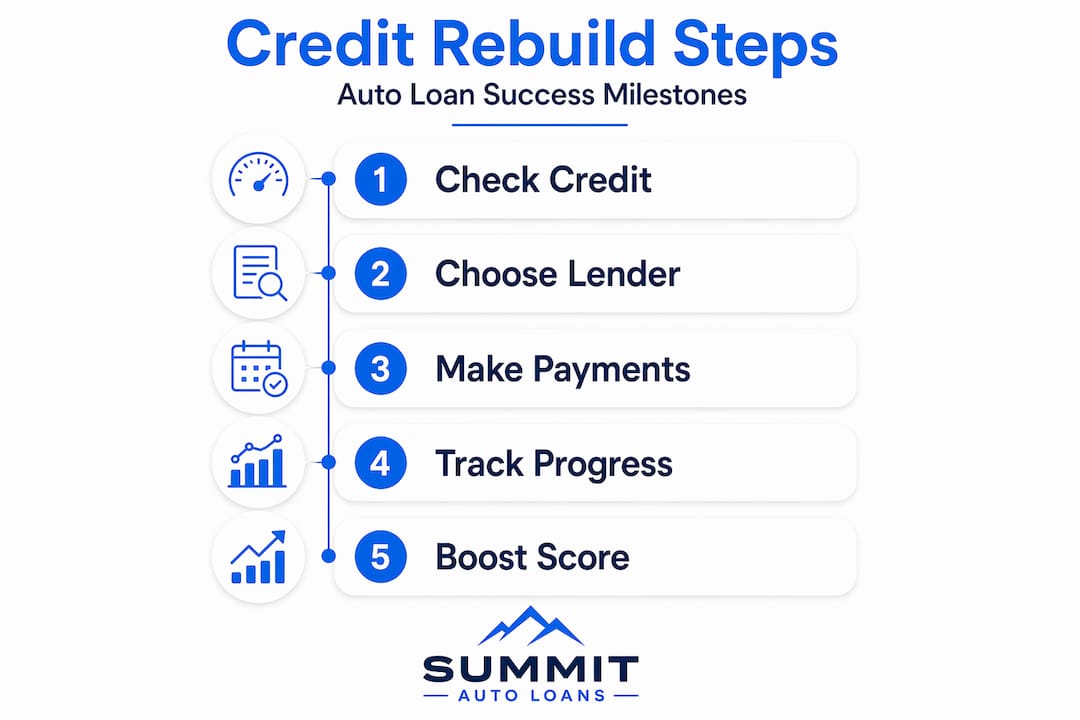
If you have three to six months before you need a vehicle, consider building a small credit foundation first. Using secured credit cards or credit-builder tools for a few months before applying for an auto loan can result in better terms and a lower overall cost. Even small improvements to your credit file before you apply make a genuine difference.
When you are ready to apply, here is how to approach it:
- Assess what you can genuinely afford. Do not stretch your budget to get a specific vehicle. A payment you cannot sustain comfortably will eventually cause you to miss one, and that sets you back significantly.
- Choose appropriate auto loan terms. Shorter terms cost less overall, but only commit to what your budget can handle every single month without strain.
- Set up automatic payments. Remove the human error factor entirely. A missed payment due to forgetfulness is a costly mistake on an auto loan you are using to rebuild.
- Avoid refinancing unless it truly lowers your total cost. Refinancing to reduce monthly payments while extending your term often means paying more overall. Refinancing is only beneficial when it reduces your total credit cost, not just your monthly obligation.
Pro Tip: Summit Auto Loans offers a auto loan calculation tool that helps you estimate your payments before you commit. Use it to plan your actual budget.
For more guidance on managing your auto loan well, Summit Auto Loans has published best practices for auto loans in Canada that are worth reviewing before you sign anything.
Comparing credit rebuilding options
A credit rebuilding car loan is one tool. Used alone, it works. Combined with others, it works faster. Here is how the main options compare:
| Credit tool | Key benefit | Main limitation | Best for |
|---|---|---|---|
| Credit rebuilding auto loan | Builds instalment credit history, provides transport | Higher overall cost for challenged credit | Those who need a vehicle and want to rebuild |
| Secured credit card | Low cost, easy to get, builds revolving credit | Small credit limit, no transport benefit | Anyone starting to rebuild credit |
| Credit-builder loan | Structured savings and credit history at once | No vehicle, funds held until loan is paid | Rebuilding credit without a major purchase |
The strongest credit recovery strategy uses more than one of these tools at the same time. A multi-tool approach that combines instalment and revolving credit demonstrates to lenders that you can handle different types of financial responsibility. For Canadians who need reliable transportation, an auto loan naturally anchors this strategy.
One important note: subprime auto loan availability has been growing year over year, which means more Canadians with credit challenges have access to these products than ever before. The market has moved in your favour.
Common challenges and how to manage them
Credit rebuilding auto loans come with real challenges. Knowing them ahead of time puts you in a much stronger position.
- Higher overall cost. Borrowers with damaged credit typically face higher costs. Accept this as the price of rebuilding and focus on the long-term credit benefit.
- Negative equity risk. If your auto loan term is too long, the vehicle may lose value faster than you pay down the balance. Choose the shortest term your budget can handle.
- Budget pressure. Life changes. Build a small financial buffer so that an unexpected expense does not translate into a missed payment.
- Impatience. The hardest part of credit rebuilding is staying consistent when progress feels slow. Trust the process. The character-based approach that good lenders use to approve these car loans is designed for people who are committed to change.
My honest take on credit rebuilding car loans
I have seen many borrowers come in expecting a quick fix and leave frustrated when their credit has not transformed in three months. That expectation is the biggest obstacle to actually succeeding.
What I have observed, time and again, is that the borrowers who treat their credit rebuilding auto loan as a long-term commitment — not a short-term solution — are the ones whose credit profiles genuinely transform within a year or two. They do not chase perfection. They just pay on time, every single month, without exception.
I also firmly believe that choosing your lender matters as much as choosing your terms. A lender who treats you like a number will not support you when things get difficult. A lender who understands your situation, like Summit Auto Loans, makes the experience far less stressful. When you feel supported rather than judged, you are more likely to stay the course and check out how to choose the right car loan for your specific situation.
Credit rebuilding is not glamorous work. But it is some of the most financially meaningful work you can do for your future self.
Start your credit rebuilding journey with Summit Auto Loans
Summit Auto Loans specialises in helping Canadians with all types of credit backgrounds access vehicle financing with confidence. Whether your credit history is damaged, limited, or complicated, their team assesses your full financial picture and works to find an auto loan that fits your life. The application process is quick, judgement-free, and designed for people who are ready to rebuild. Use the Summit Auto Loans calculator to plan your payments before you apply, or visit Summit Auto Loans directly to get pre-approved and take your first real step toward a stronger credit future.
FAQ
What is a credit rebuilding car loan?
A credit rebuilding car loan is an auto financing product for borrowers with damaged or limited credit. It works by reporting your on-time payments to credit bureaus, gradually rebuilding your credit profile over time.
How long does it take to rebuild credit with a car loan?
Most borrowers see meaningful credit recovery within 12 to 24 months of consistent on-time payments. The timeline depends on your starting point and whether you combine it with other credit tools.
Does paying off a car loan early improve credit faster?
No. Early auto loan payoff does not accelerate credit recovery. Long-term, consistent payment history is what builds your credit profile, not the speed at which you clear the balance.
Should I refinance my credit rebuilding auto loan?
Only refinance if it genuinely reduces your total auto loan cost. Refinancing purely to lower monthly payments by extending the term increases your overall cost and keeps you in debt longer, which can delay your credit recovery.
Can I combine a car loan with other tools to rebuild credit faster?
Yes, and you should. A multi-pronged approach builds your credit profile more quickly than relying on either tool alone.