Securing a low interest car loan is achievable when you align your financial profile, vehicle choice, and terms with what lenders actually look for. Low interest auto financing is the industry term for vehicle loans priced at the more affordable end of the lending spectrum, and qualifying for it comes down to preparation rather than luck. Experian’s 2025 report shows average auto loan rates of 6.80% for new cars and 11.54% for used cars, which illustrates just how much the type of vehicle and borrower profile shape the final cost. Summit Auto Loans works with Canadians across all financial backgrounds, including those with limited credit history, to find affordable vehicle financing options that fit real budgets.
How to secure a low interest car loan: your financial profile matters most
Lenders do not set auto loan pricing arbitrarily. Experian notes that lenders evaluate multiple underwriting inputs, including income, employment stability, debt-to-income ratio, vehicle loan amount, and vehicle risk factors. This means your overall financial picture carries significant weight, not just one single factor.
The most practical way to strengthen your profile before applying is to address the variables you can control:
- Income and employment stability. Lenders want to see consistent, verifiable income. Full-time employment is ideal, but self-employment with documented earnings is also accepted by many lenders, including Summit Auto Loans.
- Debt-to-income (DTI) ratio. This is the percentage of your monthly income that goes toward existing debt payments. Reducing outstanding balances on credit cards or other debt before applying lowers your DTI and signals lower risk to lenders.
- Documentation readiness. Having pay stubs, bank statements, proof of address, and government-issued identification organised before you apply speeds up the process and demonstrates financial seriousness.
- Expense management. Lenders assess whether your income, after existing obligations, comfortably covers a new car loan payment. Cutting discretionary spending in the months before applying can improve this ratio.
Borrowers with thin credit profiles can still present a strong case. Successful applicants with limited credit history focus on presenting a complete financing package, including income documentation and controlled debt, rather than relying solely on their credit history. This approach works particularly well with lenders like Summit Auto Loans, who look at the full picture.
Pro Tip: Review your monthly debt obligations and calculate your DTI before applying. If your total debt payments exceed 40% of your gross monthly income, paying down even one account can meaningfully shift your eligibility.
Does your vehicle choice affect your car loan terms?
The car you choose directly influences how a lender prices your car loan. Experian advises borrowers to select vehicles considered lower-risk by lenders, which typically means newer models with strong resale value and reliable depreciation curves. A vehicle that holds its value protects the lender if the auto loan defaults, so they reward that choice with better terms.
Here is how vehicle selection shapes your auto financing options:
- Newer vehicles generally attract more favourable vehicle loan terms because they carry lower mechanical risk and stronger resale value. Lenders are more confident in the collateral.
- Used vehicles can still be financed affordably, but vehicle loan pricing tends to be higher to account for depreciation and unknown condition. Choosing a certified pre-owned model from a reputable manufacturer reduces this concern.
- Vehicle price and auto loan amount are directly linked. A more affordable vehicle means a smaller auto loan, which reduces your total repayment obligation and monthly payment. Choosing a vehicle within your realistic budget is one of the most effective tips for low interest car loans.
- Reliability ratings matter. Vehicles with strong long-term reliability records, such as those from Toyota or Honda, tend to depreciate more slowly, which lenders view favourably when assessing collateral risk.
The best rates for car loans are not reserved only for buyers of brand-new vehicles. A well-chosen, modestly priced used vehicle with strong resale value can qualify for competitive auto financing, especially when paired with a solid financial profile. For more guidance on choosing the right auto loan for your situation, Summit Auto Loans has a detailed resource worth reading before you visit a dealership.
Steps to apply for affordable car financing
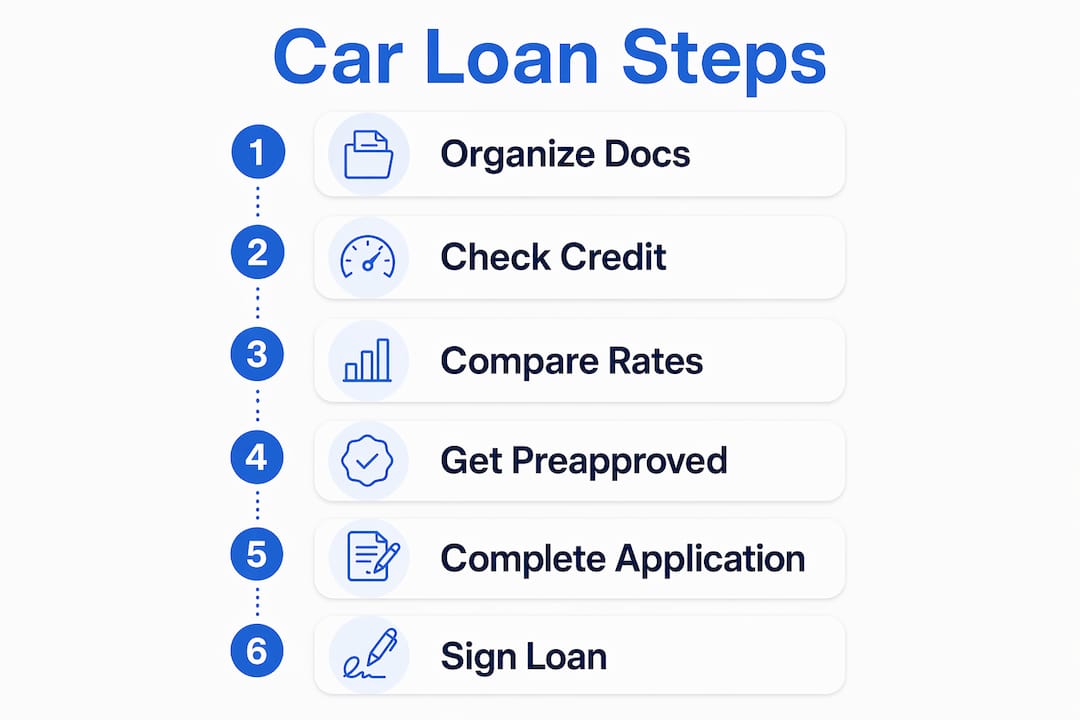
A structured approach to the application process removes guesswork and puts you in a stronger position. Follow these steps to maximise your chances of securing affordable vehicle financing:
- Gather your financial documents. Collect recent pay stubs, bank statements from the last three months, proof of address, and valid identification. Having these ready before you apply avoids delays.
- Calculate your budget using an auto loan calculator. Use the Summit Auto Loans calculator to estimate your monthly payment based on different car loan amounts and terms. This step prevents you from overcommitting to a vehicle you cannot comfortably afford.
- Apply for preapproval. Preapproval clarifies your borrowing power before you walk into a dealership. NerdWallet recommends preapproval as the most reliable way to understand your vehicle loan options and strengthen your negotiating position.
- Use your preapproval to negotiate. A preapproval letter defines your budget clearly. Dealerships are more likely to work within your terms when you arrive with confirmed vehicle financing rather than relying on in-house options.
- Review all car loan documents carefully. Before signing, confirm the total car loan cost, repayment term, and all fees. Understanding the full obligation protects you from surprises.
| Step | Action | Why it matters |
|---|---|---|
| 1 | Organise documents | Speeds up approval and demonstrates preparedness |
| 2 | Use an auto loan calculator | Sets a realistic budget before shopping |
| 3 | Get preapproved | Clarifies borrowing power and strengthens negotiation |
| 4 | Negotiate with preapproval | Reduces reliance on dealership financing terms |
| 5 | Review documents | Confirms total cost and avoids hidden fees |
Pro Tip: Multiple preapproval applications submitted within a short window are typically treated as a single inquiry. Experian confirms that multiple auto loan inquiries scored within 14 to 45 days count as one, so the temporary impact on your financial profile is minimal.
Common mistakes that increase your total auto loan cost
Many borrowers focus on the wrong numbers and end up paying far more than necessary over the life of their auto loan. Knowing where others go wrong is one of the most underrated tips for low interest car loans.
- Focusing only on monthly payments. A lower monthly payment can mean a longer car loan term, which increases the total amount you repay. TechBullion warns that long vehicle loan terms and low down payments increase total cost despite appearing affordable month to month.
- Skipping the down payment. A down payment of 10 to 20% reduces the car loan amount and lowers the risk of negative equity, where you owe more than the vehicle is worth. Even a modest down payment improves your car loan terms.
- Choosing excessively long repayment terms. Shorter uto loan terms cost less overall, even though monthly payments are higher. A 48-month term will almost always cost less in total than a 72-month term for the same vehicle.
- Not reviewing the full auto loan agreement. Fees, add-ons, and extended warranty costs can be rolled into a car loan without obvious disclosure. Read every line before signing.
The most expensive car loan is not always the one with the highest rate. It is the one with the longest term and the smallest down payment.
For Canadians with limited credit history, understanding auto loan eligibility in Alberta can clarify exactly what lenders look for and how to position yourself effectively.
What I have learned about accessible car financing in Canada
After years of observing how Canadians approach vehicle financing, the pattern I see most often is this: people with financial challenges assume their options are limited before they even apply. That assumption costs them more than any vehicle loan term ever could.
Preparation is the real differentiator. Borrowers who arrive with organised documents, a realistic budget, and a clear sense of their borrowing capacity consistently secure better outcomes than those who walk in hoping for the best. The vehicle pre-approval process is not a formality. It is the single most effective step you can take before visiting a dealership.
Summit Auto Loans stands out because it evaluates the full financial picture rather than applying a rigid filter. For Canadians in Alberta who have faced financial setbacks or are building their credit history, that approach makes a genuine difference. The goal is not a perfect application. It is an honest one.
— Harvest
Start your application with Summit Auto Loans today
Summit Auto Loans is a trusted Canadian lender serving Albertans with all types of financial backgrounds, including those with limited or no credit history. The application process is straightforward, and preapproval takes seconds. Use the auto loan calculator to confirm your budget before you apply, then get approved to understand exactly what you qualify for. There are no judgements and no unnecessary hurdles. Summit Auto Loans connects you with flexible auto financing options and a team of specialists who guide you through every step, from vehicle selection to final paperwork.
FAQ
What are the main car loan eligibility requirements in Canada?
Lenders typically assess income stability, employment status, debt-to-income ratio, and documentation such as pay stubs and proof of address. Experian confirms that lenders use multiple underwriting inputs beyond a single factor to determine auto loan terms.
How does a down payment help lower car loan costs?
A down payment of 10 to 20% reduces the total vehicle loan amount and lowers the risk of negative equity, which improves both your approval chances and the affordability of your repayment terms.
Does getting preapproved affect my financial profile?
The impact is minimal and temporary. Experian notes that multiple auto loan inquiries submitted within a 14 to 45-day window are counted as a single inquiry, making the process low-risk for borrowers.
Can I get affordable vehicle financing with limited credit history?
Yes. Lenders like Summit Auto Loans evaluate the full financial picture, including income and documentation. NerdWallet notes that choosing car loan terms carefully and managing car loan size improves affordability for borrowers with limited credit backgrounds.
What car loan term length is best for keeping total costs low?
Shorter car loan terms cost less overall, even though monthly payments are higher. TechBullion advises that long repayment terms increase total cost significantly, so choosing the shortest term your budget allows is the most financially sound approach.