Auto financing a used car in Alberta can feel like navigating a maze without a map, especially when you have a complicated credit history and every lender seems to speak a different language. This guide to used car financing breaks that maze into manageable steps, giving you the clarity you need to walk into a dealership or apply online with genuine confidence. Whether your credit is spotless, bruised, or somewhere in between, the right preparation and the right lender can make all the difference between driving home in a reliable vehicle and walking away empty-handed.
Understanding the basics of used car financing in Alberta
Used car loans work differently from mortgages or personal lines of credit, and understanding how they function locally puts you at a real advantage. When you finance a used vehicle, the car itself acts as collateral. This means the lender holds a security interest in the vehicle until you pay off the auto loan, and your monthly payments cover both principal and interest over an agreed term.
One concept every Alberta buyer needs to understand is the loan-to-value ratio, which helps lenders assess risk by comparing the auto loan balance to the car’s current market value. A lower LTV means you owe less relative to what the car is worth, and lenders consistently favour that position. For example, if a used truck is valued at $20,000 and you borrow $14,000, your LTV is 70%, which is considered healthy.
Vehicle depreciation is the hidden variable most buyers underestimate. Used cars depreciate too, and if you stretch an auto loan over six or seven years, you can easily end up owing more than the car is worth. That situation is called negative equity, and it creates a financial trap that is hard to escape. Before signing anything, also take a moment to review common myths about bad credit car loans, because misinformation can push buyers toward worse deals than they need to accept.
Key car financing concepts to keep in mind:
- The vehicle secures the auto loan, so missed payments risk repossession
- LTV directly influences your interest rate and approval odds
- Shorter terms build equity faster and cost less in total interest
- Depreciation on older vehicles can be steep, particularly in the first two years of ownership
- Understanding Alberta auto loan types helps you compare options before committing
Preparing to finance your used car purchase
Good preparation is the single biggest factor separating buyers who get strong vehicle financing deals from those who accept whatever they are offered. Budgeting is essential to understand how much you can afford monthly, including other car-related expenses like insurance, fuel, registration, and maintenance. A vehicle that fits your vehicle loan payment but strains your fuel budget is still a bad deal.
Follow these steps before you apply:
- Set your total monthly transport budget. Add up all expected costs, not just the car or truck loan payment. Most financial advisers suggest keeping total vehicle costs under 15% of monthly take-home pay.
- Research reliable used models. In Alberta’s climate, prioritise vehicles with strong cold-weather performance records and reasonable parts availability. Models like the Toyota Camry or Honda CR-V consistently hold their value well.
- Gather your documentation early. You will need proof of income, a valid government-issued ID, and details about the vehicle you intend to purchase. Refer to the required documentation to avoid delays.
- Check your credit report. Errors on your credit file can affect your approval and interest rate. Dispute anything inaccurate before applying.
- Avoid rolling over negative equity. If your current vehicle is worth less than you owe, try to pay down that gap before vehicle financing a new purchase.
Pro Tip: Use a auto loan calculation tool to estimate your monthly payments at different interest rates and term lengths before you ever speak to a lender. It removes the guesswork and keeps you from being caught off guard.
| Expense category | Estimated monthly cost (Alberta average) |
|---|---|
| Car loan payment | $350 to $550 |
| Insurance | $150 to $250 |
| Fuel | $150 to $300 |
| Maintenance and repairs | $75 to $150 |
| Registration and fees | $15 to $25 |
Executing your auto financing application with Summit Auto Loans
With your budget set and documents in hand, the application process itself becomes far less stressful. Summit Auto Loans has built their process specifically to welcome applicants from all credit backgrounds, and that intentional design makes a practical difference for Alberta buyers who have been turned away elsewhere.
Here is how the process typically unfolds:
- Start your application online. The approval process is built for speed and accessibility. You can receive a pre-approval decision quickly without the kind of hard credit inquiry that damages your score.
- Be upfront about your situation. Summit Auto Loans works with flexible financing options designed to accommodate varied credit histories. Transparency on your part helps them match you with the right auto loan structure.
- Submit your documents promptly. Once you have identified the vehicle, provide all supporting documentation together to avoid back-and-forth delays.
- Review your car loan terms carefully. Confirm the interest rate, total vehicle loan cost, term length, and any fees before signing. A good lender will explain every line item without hesitation.
Pro Tip: Stay in direct communication with your vehicle loan adviser throughout the process. A quick phone call can resolve a documentation question in minutes rather than days, keeping your purchase timeline on track.
Common pitfalls and how to avoid negative equity when auto financing used cars
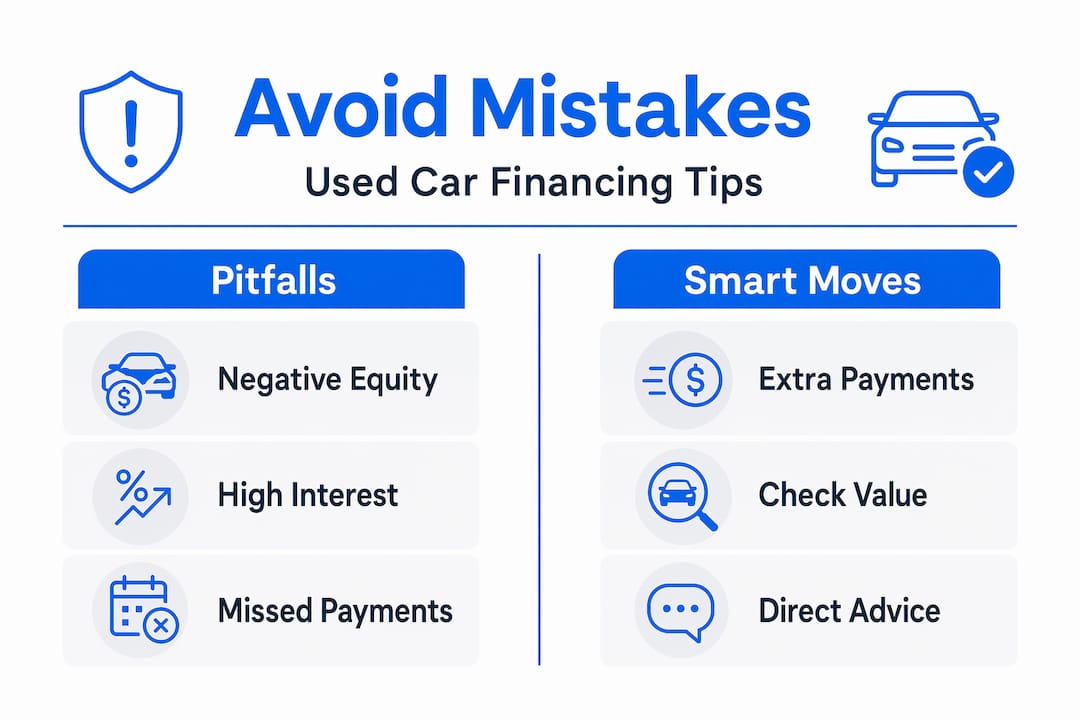
Negative equity is not just an inconvenience. Rolling negative equity into a new car loan significantly increases the risk of repossession and long-term financial strain, because you start every new car loan already underwater.
“The biggest risk is you never get out of it, and it just keeps compounding.” — Jessica Caldwell, Edmunds expert
Here is how to protect yourself:
- Make a meaningful down payment. Even 10 to 20% down reduces your LTV immediately and improves your interest rate in most cases
- Choose the shortest term you can afford. A 48-month term costs more per month than a 72-month term, but you build equity faster and pay significantly less interest overall
- Read every clause in your agreement. Administrative fees, early repayment penalties, and dealer add-ons can quietly inflate your total car loan cost
- Track your vehicle’s market value quarterly. Free tools exist online that estimate your car’s current resale value, and staying aware of that number helps you make informed decisions
- Avoid skipping payments. Even one missed payment can set off a chain of late fees and credit damage that makes refinancing harder later
Reviewing common car financing mistakes before you sign keeps you from learning these lessons the expensive way.
Ensuring successful car loan repayment and protecting your investment
Securing the car loan is only half the job. How you manage repayment determines whether this vehicle becomes a genuine financial asset or a persistent source of stress.
- Set up automatic payments. Automatic payment plans help you avoid late fees and support consistent repayment without relying on memory
- Make extra principal payments when possible. Even an extra $50 per month applied directly to principal can shorten a 60-month car loan by several months and save you meaningful interest
- Maintain your vehicle diligently. Regular oil changes, tyre rotations, and timely repairs preserve the car’s resale value, which directly protects your equity position
- Keep your insurance current. If your lender recommends gap insurance, take it seriously. Gap coverage pays the difference between what you owe and what the car is worth if it is written off
- Communicate early if you face payment trouble. Contact Summit Auto Loans at the first sign of difficulty. Proactive communication opens the door to restructuring options that a last-minute call will not.
Rethinking the path to accessible used car financing in Alberta
Here is an opinion you will not hear often in mainstream financial media: the traditional credit-score-first lending model does not just inconvenience buyers with imperfect histories, it actively prevents many working Albertans from accessing reliable transportation, which in turn limits their employment options and economic mobility. The model punishes people for the exact circumstances that made building credit difficult in the first place.
Inclusive auto financing, as practised by lenders who take a whole-picture view of an applicant, is not charity. It is a smarter risk assessment. Someone who has been steadily employed for three years and pays rent on time is a better credit risk than their credit score might suggest. Rigid score-based gatekeeping misses this entirely.
“Accessible car loan solutions foster independence and opportunity for those with past credit challenges.”
The flexible car financing approach that Summit Auto Loans has built is not just a niche product for desperate buyers. It is a more honest model that reflects how real financial lives actually work. More lenders in Alberta should be willing to look past a number and ask better questions.
How Summit Auto Loans can help you finance your used car purchase
Summit Auto Loans was built for exactly the situation this article describes: Alberta residents who need reliable transportation and deserve a car or truck financing process that respects their circumstances. Their application is designed for all credit backgrounds, their advisers explain every step clearly, and there are no unpleasant surprises buried in the fine print.
Use their car loan payment calculator to understand your numbers before you commit, then move directly to the approval application when you are ready to act. The entire experience is built to remove barriers, not create them. Visit Summit Auto Loans to get started.
Pro Tip: Apply for pre-approval early in your vehicle search. Knowing your approved budget before you shop keeps negotiations straightforward and prevents you from falling in love with a car outside your range.
Frequently asked questions
What documents do I need to apply for a used car loan in Alberta?
You typically need proof of income, valid ID, vehicle details, and proof of insurance to apply for auto financing in Alberta. Having these ready before you apply speeds up the approval process considerably.
How does Summit Auto Loans handle applications from people with bad credit?
They offer flexible vehicle financing options that welcome all credit histories without invasive checks, making approval accessible to applicants who have been declined elsewhere. The focus is on your current ability to repay, not just your past credit score.
What is negative equity and why should I avoid it?
Negative equity happens when you owe more on your loan than the car is currently worth, and rolling it into a new vehicle loan raises your repossession risk and total debt substantially. Avoiding it keeps your vehicle financing position healthy and your options open.
Can I improve my vehicle loan-to-value ratio over time?
Yes. Making extra principal payments and maintaining your vehicle to preserve its resale value are the two most direct ways to improve your LTV as the car loan progresses. Both actions strengthen your financial standing and can make refinancing at a better rate more accessible.