Needing reliable transportation in Alberta when you have no credit history feels like a frustrating catch-22: you need a car to get to work, but lenders want credit history you haven’t had the chance to build yet. The good news is that thousands of Albertans successfully finance vehicles every year without an established credit profile. Alberta also has specific provincial rules that offer you protections most Canadians aren’t aware of. This guide walks you through every stage, from gathering your documents to signing the final paperwork safely.
Key Takeaways
| Point | Details |
|---|---|
| Start with preparation | Gather your documents and check your credit status before you shop for a car. |
| Know your loan options | Compare Alberta lenders, approval criteria, and interest rate limits before choosing a car loan. |
| Avoid costly mistakes | Check for liens, read the full loan agreement, and calculate your true total cost to stay safe. |
| Build future credit | A car loan responsibly managed can improve your credit for bigger financial milestones ahead. |
What you need before shopping for a car
Before you even walk into a dealership or apply online, it helps to be prepared. Lenders approving buyers with no credit are taking on more risk, so they lean heavily on documentation to fill the gaps.
Here are the essential documents you should gather before applying:
- Government-issued photo ID (Alberta driver’s licence or passport)
- Proof of Alberta address (utility bill, lease agreement, or bank statement dated within 90 days)
- Proof of stable income (recent pay stubs, a letter of employment, or tax returns if you’re self-employed)
- Bank statements from the last three months showing regular deposits
- References (some lenders ask for two or three personal or professional references)
- Social Insurance Number (required for credit bureau checks)
Your auto loan requirements checklist should be ready before your first application. Missing even one document can delay or kill your approval.
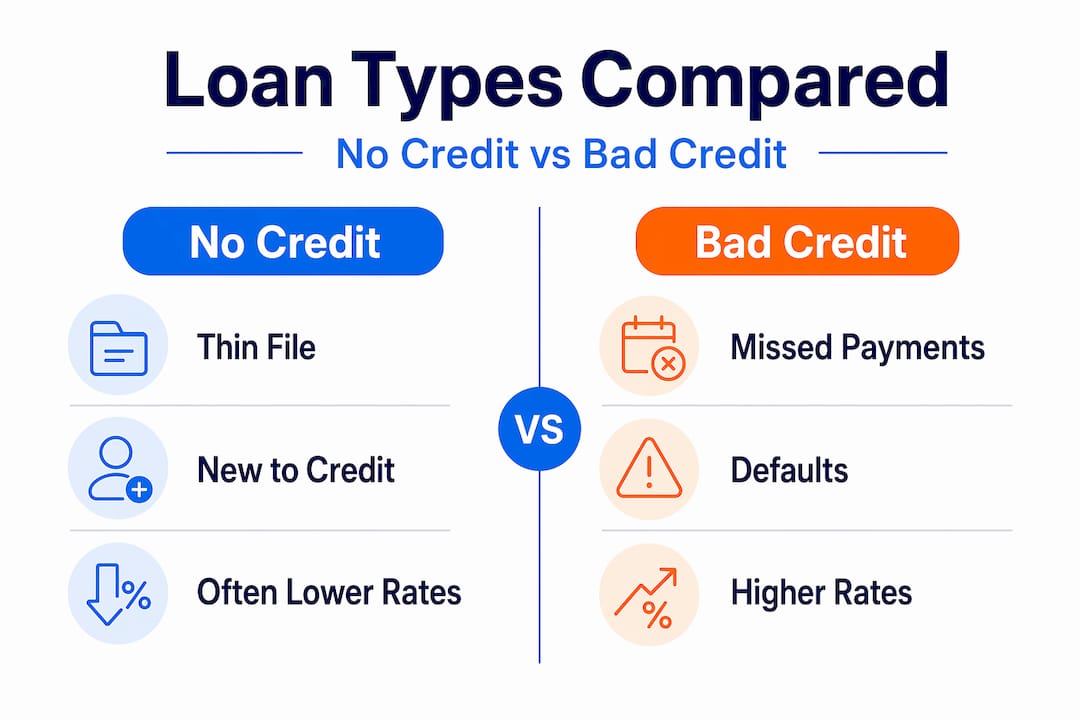
Next, understand where you actually stand. “No credit” and “bad credit” are not the same thing. No credit means your credit file is thin or completely empty, often the case for newcomers to Canada or young adults. Bad credit means you have a history but it includes missed payments, collections, or defaults. Knowing the difference matters because it shapes which lenders will work with you and what terms to expect. Review your vehicle loan eligibility in Alberta so you can set realistic expectations.
You can request your credit report for free through Equifax or TransUnion Canada. Even if you believe you have no credit, check your credit report first, because errors or surprise accounts can affect your file. Guidance from NerdWallet Canada consistently emphasises checking your credit report first and using the least risky credit-building options when your file is thin.
| Document | Why lenders need it | Where to get it |
|---|---|---|
| Photo ID | Confirms identity | ServiceAlberta or passport office |
| Proof of income | Shows repayment ability | Your employer or CRA |
| Bank statements | Verifies cash flow | Your financial institution |
| Proof of address | Confirms Alberta residency | Utility provider or landlord |
Pro Tip: Even a modest down payment of $500 to $2,000 can significantly boost your approval odds when you have no credit. If you have a vehicle to trade in, that equity counts too. It reduces the lender’s risk and often lowers your monthly payment.
Comparing your car loan options in Alberta
Once you’ve got your paperwork ready, it’s time to compare financing options designed for no or low credit buyers. Not all lenders treat applicants the same way, and in Alberta, the law draws clear lines around what lenders can charge.
Your main options are:
- Banks and credit unions typically require an established credit score and are unlikely to approve thin-file applicants without a co-signer.
- Franchise and independent dealerships often have relationships with specialty lenders who work with no-credit buyers, though rates can be higher.
- Online auto financing specialists like Summit Auto Loans focus specifically on Albertans with no or poor credit and can often provide faster decisions.
Understanding the bad credit vs no credit auto loans distinction helps you target the right lender from the start.
| Lender type | Typical approval speed | Min. down payment | Avg. APR range | Best for |
|---|---|---|---|---|
| Banks/credit unions | 3 to 7 days | 10 to 20% | 6 to 12% | Established credit |
| Franchise dealerships | 1 to 2 days | 5 to 15% | 10 to 25% | Mid-range credit |
| Online specialists | Same day | 0 to 10% | 8 to 29% | No or poor credit |
Alberta’s high-cost credit regulation means that any lender offering an annual rate of 32% or more must comply with specific provincial rules, including detailed disclosure requirements and cooling-off periods. Federally, Canada’s criminal rate threshold moved to 35% APR effective January 1, 2025, meaning any loan above that rate is illegal.
These protections matter because some lenders targeting no-credit buyers push rates dangerously close to those limits. Explore flexible auto financing options and review Alberta auto loan types to understand what structures are available.
Red flags to watch for:
- Pressure to sign the same day without time to review
- No written disclosure of total cost and APR
- Add-ons like extended warranties bundled into the price without explanation
- Verbal promises that don’t appear in writing
Pro Tip: Always ask for the total cost of borrowing, not just the monthly payment. A low monthly payment stretched over 84 months can cost you thousands more than a slightly higher payment over 48 months.
How to apply and get approved with no credit
After comparing your options, you’re ready to apply and see what you qualify for. The process is more straightforward than most people expect.
- Submit your application online or in person, providing all required documents upfront.
- Verify employment and income by having your employer available to confirm your status if contacted.
- Select your vehicle within the budget the lender pre-approves to avoid surprises later.
- Review your loan offer carefully, paying attention to the APR, total interest payable, term length, and any fees.
- Sign documentation only once you fully understand all terms and have had time to read everything.
Common mistakes that sink approvals include submitting incomplete applications, providing inaccurate income figures, or applying to too many lenders at once without a plan. Knowing how to qualify for car financing in Alberta ahead of time saves you from these pitfalls.
Always review your financing offer for total cost and term length before accepting. A lower monthly payment is not always a better deal.
When it comes to multiple applications, there is a practical strategy. Each credit application creates an inquiry on your file, which can nudge your score down slightly. However, credit bureaus typically group multiple auto loan inquiries made within a 14 to 45 day window as a single inquiry, recognising you’re rate shopping. Apply to a shortlist of reputable lenders within a short window rather than spreading applications over several months.
One of the biggest long-term benefits of this process: a car loan that reports to the credit bureaus will help you build your credit with every on-time payment. Studies consistently show that payment history accounts for roughly 35% of your credit score, making a car loan one of the fastest practical ways to establish a strong file.
Protecting yourself: liens, fees, and risky offers
Even after approval, a few more checks can save you serious money and stress. The vehicle itself deserves as much scrutiny as the loan terms.
Before you finalise any used vehicle purchase, the Alberta Personal Property Registry PPSA lien search is critical. A lien means a previous owner borrowed money against the vehicle and it may still be outstanding. If you buy a vehicle with an existing lien, you could legally lose it to the creditor even after paying for it yourself.
Know Alberta’s high-cost loan limits. Any lender at or above 32% APR must provide you with a written cost-of-credit disclosure and a two-business-day cancellation right. If they don’t, that’s a serious warning sign.
Here’s a numbered checklist to protect yourself before signing anything:
- Run a PPSA lien search using the vehicle’s VIN through the Alberta Personal Property Registry.
- Request a complete written breakdown of the loan, including APR, fees, insurance add-ons, and total repayment amount.
- Verify the dealer or lender is licensed in Alberta.
- Review every add-on item (rust protection, extended warranty, GAP insurance) and confirm whether each is mandatory or optional.
- Take 24 hours before signing if you feel any pressure, it’s your right.
Review essential questions to ask about financing and use car loan documentation tips to make sure nothing slips through. Be aware that some brokers bundle hidden costs into deals that inflate your total obligation significantly.
The truth about ‘no credit, no problem’ car loans in Alberta
Here’s what we’ve learned from years of helping Albertans find the right car: the phrase “no credit, no problem” is often marketing, not a guarantee.
Some offers targeting no-credit buyers are structured to maximise profit at your expense. Vehicles offered under these programmes are sometimes older with high mileage, payment terms are stretched to make monthly amounts look affordable while total interest balloons, and fees are buried in paperwork few buyers read carefully. We’ve seen buyers end up paying $18,000 for a vehicle worth $9,000 simply because they focused on the monthly number.
The proven path is patience and preparation. Ask every question. Never feel pressured to sign on the spot. A legitimate lender will always give you time to review your offer. Understanding how vehicle delivery works can also help you set expectations around the full process.
What most guides miss is the long-term picture. The financial habits you establish with this first loan ripple forward. Pay on time, every month, and within 12 to 24 months you’ll likely qualify for significantly better rates on your next vehicle, a mortgage, or a personal line of credit. This loan isn’t just about getting a car. It’s the foundation of your entire Canadian credit story.
Pro Tip: If an offer in Alberta seems too good to be true, ask for the full written cost-of-credit disclosure before you respond. If the lender hesitates to provide it, walk away.
How Summit Auto Loans helps Albertans with no credit
If you’re ready to take the next step confidently, Summit Auto Loans is built specifically for this situation. We specialise in helping Albertans with no credit or poor credit get into reliable vehicles without the stress and judgement that comes with traditional lenders. You can get approved today through our fast online pre-approval process, or calculate your loan payment to understand your realistic budget before you shop. With locations across Alberta, our team of financing specialists is ready to walk alongside you, answer every question, and match you with a vehicle and loan that genuinely fits your life and income.
Frequently asked questions
Can I really get approved for a car loan in Alberta with no credit history?
Yes, many Alberta lenders and dealers offer programmes specifically for buyers with no credit, though requirements and rates will vary based on income and down payment. Guidance for thin-file applicants consistently points to documenting income and considering a down payment to strengthen your application.
What is the highest interest rate allowed for car loans in Alberta?
Under Alberta’s high-cost credit rules, lenders must comply with special requirements at 32% APR, and Canada’s updated criminal rate cap of 35% APR, effective January 1, 2025, sets the absolute legal ceiling.
How do I check if a used car in Alberta has a lien?
Use the Alberta PPSA lien check by VIN before purchasing to confirm any registered security interests on the vehicle.
Should I make a down payment if I have no credit?
A down payment increases approval odds and can lower your interest rate, particularly when your credit file is thin or nonexistent. Even a small amount shows lenders you’re financially committed.
Can a car loan help me build my credit in Canada?
Yes, regular on-time payments on a car loan reported to the credit bureaus are one of the most effective ways to establish credit from scratch in Canada.