
Feeling shut out of car financing because of a rough credit history is one of the most frustrating experiences for hardworking Albertans. You need reliable transportation to get to work, take care of your family, and manage daily life, yet a low credit score can make it feel like every door is closed. The good news is that qualifying for car financing with bad or no credit in Alberta is entirely possible when you understand what lenders actually look for, what documents to prepare, and which steps to follow. This guide breaks it all down clearly so you can move forward with confidence.
What you need to qualify for car financing in Alberta
Now that you know approval is possible, let’s clarify exactly what you need to qualify in Alberta. The requirements are more straightforward than most people expect.
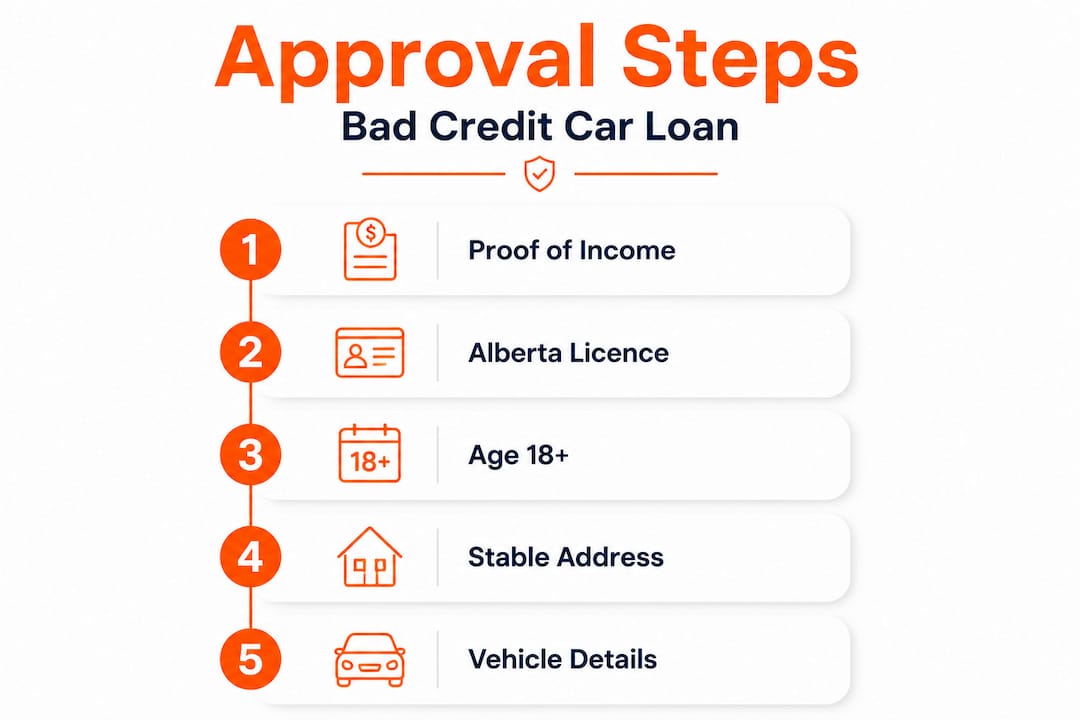
First, the basics. You must be an Alberta resident, at least 18 years old, and hold a valid Alberta driver’s licence. Beyond that, lenders focus heavily on your income and employment stability rather than your credit score alone.
Income and employment requirements
Most subprime lenders require a minimum gross monthly income of $1,200 to $2,000 before taxes, though this varies by lender. Stable employment of six months or more is preferred, but it is not always a hard rule. Government benefits like AISH (Assured Income for the Severely Handicapped), which pays $1,685 per month, often qualify as acceptable income.
Credit score expectations
Here is where many Albertans are pleasantly surprised. There is no strict minimum credit score for subprime lenders. Scores below 575, no credit history at all, past bankruptcies, and consumer proposals are all situations that specialty lenders regularly work with. They evaluate your overall financial picture rather than a single number.
| Requirement | Standard bank | Subprime lender |
|---|---|---|
| Minimum credit score | 650+ | No minimum |
| Employment history | 2+ years preferred | 6 months preferred |
| Monthly income | $2,500+ | $1,200 to $2,000 |
| Bankruptcy or proposal | Usually declined | Often approved |
| AISH or benefits | Rarely accepted | Commonly accepted |
Key eligibility points at a glance:
- Alberta residency and valid driver’s licence
- Age 18 or older
- Stable income (employment, AISH, CPP, EI, or other qualifying benefits)
- Willingness to provide documentation (more on this below)
- A co-signer can strengthen your application but is not required in most cases
Pro Tip: If you are actively working on building your credit while applying, mention it to your auto financing specialist.
It is also worth knowing that many of the bad credit car loan myths floating around online, like “you must have a co-signer” or “you need a perfect repayment history,” simply are not true for Alberta’s subprime market.
“The biggest mistake people make is waiting until their credit is ‘perfect’ before applying. Specialty lenders are designed for exactly the situation you’re in right now.”
The real secret to approval: what lenders don’t advertise
Here is something most SUV, car or truck financing articles skip over entirely. Traditional banks and credit unions like ATB Financial operate with rigid credit thresholds, typically requiring scores above 650 and stable employment histories that fit neatly into a box. If your situation is messier, they decline you, not because you are a bad borrower, but because their systems are not built for nuance.
Subprime dealerships and brokers, on the other hand, specialise in exactly that nuance. They understand that a consumer proposal does not make someone irresponsible. They know that AISH recipients are actually very reliable borrowers because their income is consistent and non-garnishable. They recognise that someone who has been through bankruptcy has already dealt with their debt and is often in a stronger financial position than before.
The real lever in any bad credit application is not your score. It is the story your documents tell. Stable address, consistent income, reasonable debt load, and a clear ability to make payments, these signals matter far more than a three-digit number. Lenders who specialise in this space are trained to read that story.
Ready to take the next step? Fast-track your Alberta car financing
If this guide has answered your questions, the next move is simple. At Summit Auto Loans, we work with Alberta residents across all credit situations, from first-time buyers with no credit history to those rebuilding after bankruptcy. Our quick approval application takes just minutes. Approval is faster than you think, and reliable transportation is closer than it feels right now.


