
Finding an affordable auto loan in Alberta can feel overwhelming, especially when you have less-than-perfect credit and worry about landing in expensive, high-interest debt. Many Albertans face a frustrating reality: quick approvals often come loaded with hidden fees, steep rates, and fine print that drives up the real cost of borrowing. Alberta does have regulatory protections around high-cost credit, but knowing how to use them is the difference between a manageable monthly payment and years of financial strain. This step-by-step guide walks you through exactly how to prepare, qualify, apply, and verify affordability so you can drive away with confidence.
Key Takeaways
| Point | Details |
|---|---|
| APR matters in Alberta | If your auto loan APR, including fees, reaches 32%, it’s regulated as high-cost credit. |
| Qualification requirements | Prepare your documents and understand lender standards to improve your chances of affordable approval. |
| Application steps | Follow a clear process using calculators, rate reviews, and fast approval strategies to secure the best deal. |
| Verification is critical | Double-check APR and auto loan terms for hidden costs before signing to ensure true affordability. |
Understanding Alberta’s auto loan regulations
Before you fill out a single application, you need to know the rules governing auto financing in your province. Alberta has specific legislation designed to protect borrowers from predatory lending, and understanding it puts real power in your hands.
Alberta.ca defines high-cost credit as any credit product with a rate of 32% or more, including auto loans. That threshold is the single most important number to keep in mind throughout the entire auto financing process. If your vehicle loan’s annual percentage rate (APR) hits or exceeds 32%, you are automatically in a regulated category with stricter lender obligations and additional consumer protections.
What exactly is APR? It stands for annual percentage rate, and it represents the true yearly cost of borrowing, including not just the interest rate but also mandatory fees rolled into the car loan. This is why a car loan advertised at a low interest rate can still push past the 32% threshold once all the fees are counted. Always ask lenders to disclose the full APR, not just the nominal interest rate.
Here is a quick snapshot of how the threshold affects you:
| APR range | Regulatory category | Key implication |
|---|---|---|
| Under 32% | Standard credit product | Fewer mandatory disclosures |
| 32% or higher | High-cost credit product | Stricter lender obligations apply |
| 32% or higher | High-cost instalment car loan | Borrower has right to cancel within 2 days |
A few things that factor into whether your vehicle loan qualifies as high-cost credit:
- Interest rate charged annually
- Mandatory administration fees added at origination
- Insurance premiums if required by the lender
- Any other compulsory charge that forms part of the credit agreement
“If you are comparing vehicle loan offers, always ask for the APR including all mandatory fees. That is the only honest apples-to-apples comparison you can make.”
Asking the right questions before car financing is a habit that protects your wallet long before you sign anything. You can also use a car loan term price prediction tool to model how different terms affect total vehicle loan cost over time.
What you need to qualify for an affordable auto loan
With clear regulatory knowledge, next comes preparing your application. Lenders will expect specific documents and information, and arriving prepared dramatically speeds up your approval and improves your chances of securing a better rate.
Most Alberta lenders look for the following when assessing an auto loan application:
- Proof of income: Recent pay stubs, employment letter, or tax returns for self-employed applicants
- Proof of residence: A utility bill, lease agreement, or bank statement showing your Alberta address
- Government-issued ID: A valid driver’s licence or passport
- Credit history: Pulled directly by the lender, but knowing your score ahead of time helps you negotiate
- Banking information: To verify your ability to handle monthly payments
Your credit history matters a great deal, but it is not the final word. Many lenders serving Alberta residents will work with applicants who have bruised credit, recent collections, or even prior bankruptcies, provided the income is stable and the debt-to-income ratio is manageable. If your offer’s APR is 32% or higher, you are inside the province’s high-cost credit regulatory regime, which actually gives you additional rights as a borrower.
| Situation | Impact on approval | Strategy |
|---|---|---|
| Good credit (680+) | Easiest approval, lowest rates | Shop multiple lenders to negotiate |
| Fair credit (600-679) | Moderate approval, mid-range rates | Provide strong income proof |
| Bad credit (below 600) | Harder approval, higher rates | Focus on income stability and down payment |
| No credit history | Limited data, lender-dependent | Consider a co-signer or secured option |
Pro Tip: Check your credit report for errors before applying. A single incorrect collection account can drop your score by 50 to 100 points, costing you hundreds of dollars per year in interest. Disputes can be filed directly through Equifax Canada or TransUnion Canada for free.
Review the complete auto loan requirements checklist to make sure you have everything ready before submitting. Understanding auto loan eligibility in Alberta can also save you from applying to lenders who are unlikely to approve your profile.
Step-by-step: Applying for an affordable auto loan in Alberta
You are ready to apply. Here is the detailed, step-by-step process to follow so you avoid overpaying and maximise your chances of fast approval.
Set a realistic budget. Before looking at vehicles, calculate exactly how much you can afford monthly. A general guideline is to keep your total vehicle costs under 15% of your gross monthly income, including insurance and fuel.
Use an auto loan calculator. Run numbers through a reliable auto loan calculator to test different loan amounts, terms, and rates. This gives you a clear picture of your payment range before any lender sees your application.
Get pre-approved. Pre-approval gives you bargaining power at any dealership. It also helps you spot lenders offering suspicious rates before you are emotionally attached to a specific vehicle.
Review the full APR. This is the step most buyers skip. Alberta regulates high-cost credit at 32% APR or more, including both rates and fees. Ask for a full cost of borrowing disclosure before you accept any offer.
Submit your documentation. Have your pay stubs, ID, and proof of address ready digitally. Many lenders now accept uploaded documents, which speeds up the approval timeline significantly.
Compare at least two or three offers. Never accept the first offer without comparison. Even a 2% difference in APR on a $25,000 loan over 60 months adds up to roughly $1,500 in extra interest paid.
Confirm your approval in writing. Once you accept an offer, get all terms in writing before transferring any funds or driving off the lot.
If bad credit is your main concern, understanding how to qualify with bad credit gives you specific strategies to strengthen your application. It is also worth understanding the difference between bad credit and no credit because the approval approach varies meaningfully between the two situations.
“The fastest approvals are not always the best ones. A lender who takes two extra days to provide a clear cost disclosure is worth the wait.”
How to verify that your vehicle loan is genuinely affordable
After applying, verify your auto loan’s affordability before signing any agreement. This step is where many Albertans get caught off guard.
Start by confirming the full APR calculation. APR including mandatory fees must stay under 32% to avoid high-cost credit oversight in Alberta. If your lender cannot or will not provide this number clearly, that is a significant red flag.
Here is a verification checklist to work through before you sign:
- Confirm APR includes all mandatory fees, not just the base interest rate
- Read the entire auto loan agreement, paying attention to prepayment penalties and default clauses
- Identify any optional add-ons like extended warranties or gap insurance being bundled without your explicit consent
- Verify the vehicle loan term matches what you discussed verbally
- Check the total amount payable, which is the principal plus all interest and fees over the full auto loan period
Pro Tip: If the total amount payable seems dramatically higher than the vehicle’s purchase price, ask the lender to break down every charge line by line. Legitimate lenders will do this without hesitation.
One underutilised approach is checking out auto loan types designed for fast approval to ensure you are in the right product category from the start. Certain car loan structures are simply better suited to different credit profiles, and picking the right one upfront reduces the risk of hitting that 32% threshold.
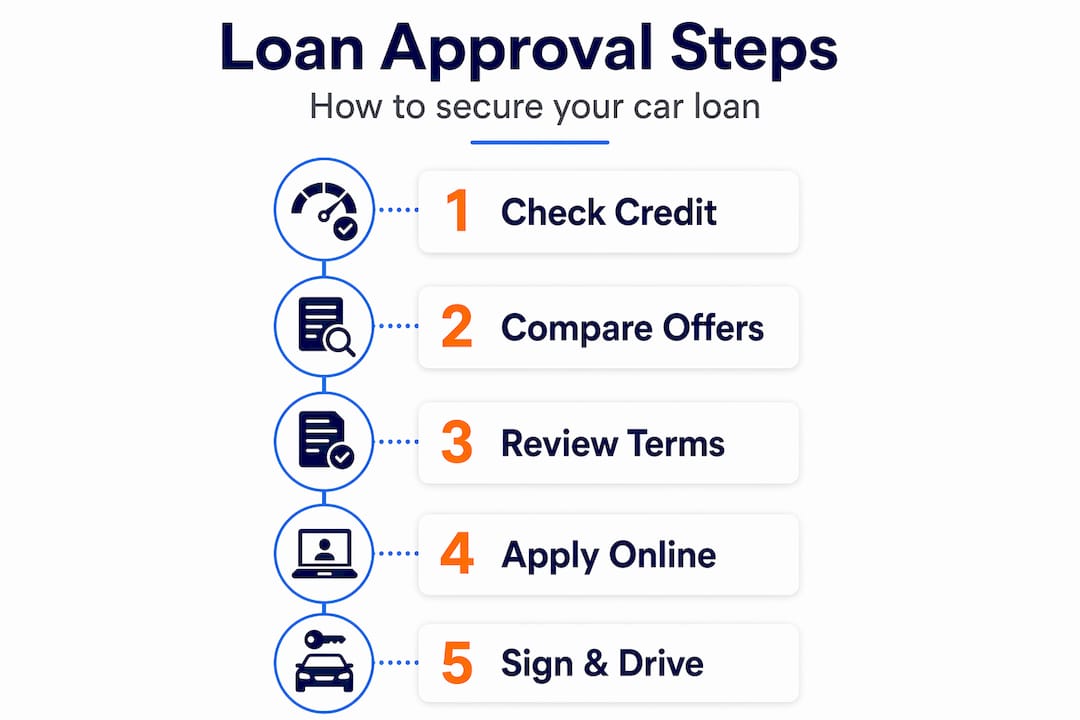
If the terms feel off or the numbers do not add up after your review, negotiate or walk away. You are never obligated to sign.
An insider’s take: Avoiding costly mistakes with Alberta auto loans
Here is what most car financing guides will not tell you. The biggest financial mistakes Albertans make with auto loans have almost nothing to do with interest rates and everything to do with focus. When buyers fixate on the monthly payment, lenders gain enormous flexibility to extend car loan terms, bury fees, and push APRs toward the regulatory edge without anyone noticing.
A $450 monthly payment sounds reasonable until you realise the autoloan runs 84 months, the total interest paid exceeds $6,000, and the vehicle will be worth half its value before you are halfway through repayment. The monthly payment is not the cost of the auto loan. The APR over the full term is.
Another trap is treating Alberta’s 32% threshold as a ceiling rather than a warning sign. The regulation exists to protect you, not to tell you what is acceptable. Most Albertans should be aiming for rates well below that level. If you are being quoted anything above 20%, it is worth exploring whether a larger down payment, a less expensive vehicle, or a co-signer could bring that rate down before you commit.
Negotiating is also far more possible than most buyers realise. Lenders compete for business, and asking the critical questions for Alberta car buyers often reveals room to reduce fees or improve terms. The buyers who get the best deals are the ones who come prepared, ask pointed questions, and are willing to pause the process rather than rush into a signature.
Next steps: Find your affordable auto loan in Alberta
You now have a complete picture of how to approach auto financing in Alberta strategically. At Summit Auto Loans, we work with Albertans across all credit backgrounds, including those who have been turned away elsewhere. Our process is built around speed, transparency, and getting you into a reliable vehicle without the stress. Learn how the process works from pre-approval to delivery, use our auto loan calculator to test your numbers before committing, or go ahead and get approved today. We review applications quickly and provide clear terms so you always know exactly what you are agreeing to.
Frequently asked questions
What APR triggers Alberta’s high-cost credit regulations for auto loans?
Any APR at or above 32%, including all mandatory fees, makes an auto loan a regulated high-cost credit product in Alberta, which triggers additional lender obligations and borrower protections.
Can I get an affordable auto loan in Alberta even with bad credit?
Yes, many lenders offer options for Canadians with less-than-perfect credit, but always confirm that your APR stays below 32% to avoid entering the high-cost credit regulatory regime, regardless of your credit score.
What should I look for to ensure my auto loan is affordable?
Review the full APR including all fees, check the final agreement for hidden costs and prepayment penalties, and verify compliance with Alberta’s 32% threshold before you put your signature on anything.
Are online car loan calculators useful for Alberta car buyers?
Absolutely. Reliable calculators help you model payments and compare offers across different car, SUV or truck loan terms, but always cross-reference the APR and fees against Alberta’s regulatory requirements to make sure the offer is genuinely affordable.


