Many Canadians assume that what is no credit auto financing is simply another way of saying “you can’t get a car loan.” That’s not true. No credit auto financing is a real, accessible option designed for people who have never borrowed before, not for people who have borrowed badly. The difference matters enormously, and understanding it puts you in a much stronger position. Whether you are a newcomer to Canada, a young adult buying your first vehicle, or someone who has simply never used credit, you have more options than you think.
What no credit auto financing actually means
Here is something most people get wrong right away. No credit differs from bad credit in a fundamental way. Bad credit means you have a borrowing history that includes missed payments, defaults, or collections. No credit means you have little to no borrowing history at all. There is nothing negative on record. You are simply a blank slate.
Traditional banks find blank slates uncomfortable. Their approval systems are built around historical data, and when there is no data, the system often defaults to rejection. That is where specialised lenders come in.
Auto financing without credit works by shifting the focus away from your past behaviour and toward your present financial situation. Lenders who specialise in this area evaluate you on different criteria entirely:
- Employment stability: How long have you been with your current employer?
- Income level: Do you earn enough to comfortably cover monthly payments?
- Debt-to-income ratio: Are your current financial obligations manageable relative to what you earn?
- Residency and identification: Proof that you are who you say you are and that you live where you say you live.
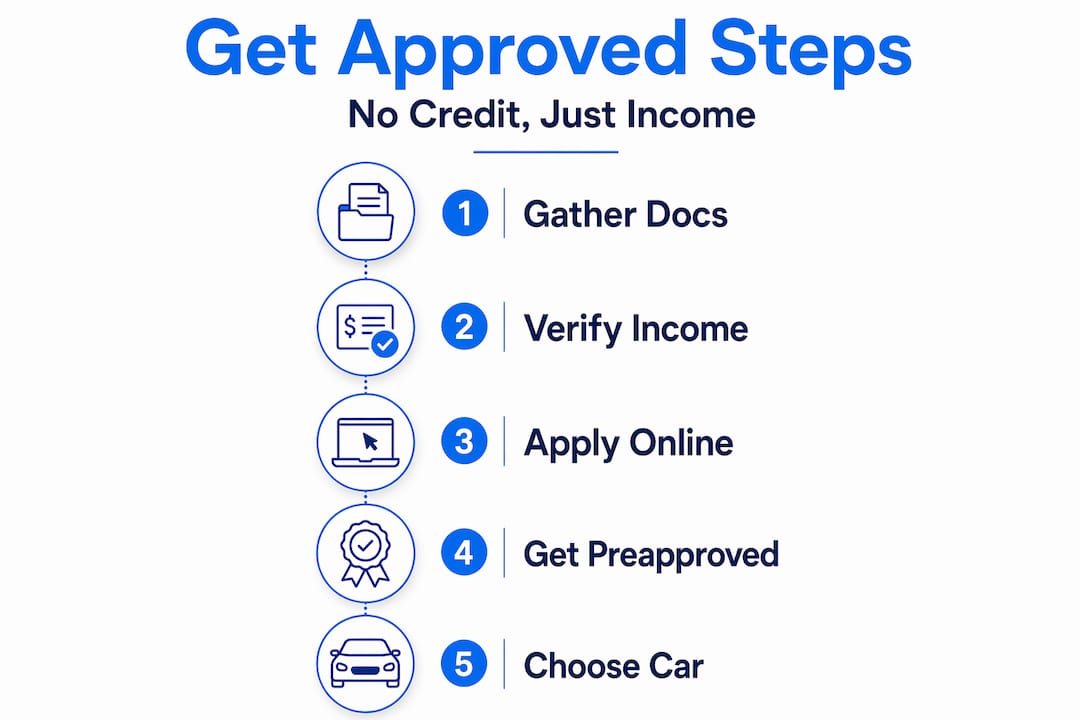
Some lenders offer preapproval based on income verification alone, giving you a realistic picture of your auto loan terms before any formal commitment. Summit Auto Loans approaches car financing this way, making the process far less stressful for people who are new to borrowing.
What you need to qualify
Knowing what lenders look for takes most of the guesswork out of the process. Here is a practical breakdown of what to prepare before you apply for no credit auto financing in Canada.
- Proof of income. Lenders typically require a minimum monthly income of around $1,800, verified through recent pay stubs or bank statements. Self-employed applicants may need to provide additional documentation such as tax returns or bank records covering several months.
- Employment verification. A letter from your employer or recent pay stubs confirming your current position help demonstrate stability.
- Bank statements. These show your day-to-day financial behaviour, even without a formal credit history.
- Government-issued identification. A valid driver’s licence and one additional piece of ID are standard.
- Proof of residence. A utility bill or lease agreement in your name confirms your address.
The good news is that lenders focused on income and employment rather than credit history are far more flexible than traditional banks. They look at your debt-to-income ratio, ideally below 44%, to determine how much of a monthly payment you can realistically handle.
Pro Tip: Gather all your documents before you apply. Having pay stubs, bank statements, and ID ready in advance speeds up the approval process considerably and signals to the lender that you are organised and serious.
Pitfalls and misconceptions to watch out for
Options for car financing without credit are real, but not all of them are equally good for you. There are a few traps that catch people off guard, and being aware of them can save you a significant amount of money and frustration.
One of the most consequential pitfalls is choosing a lender who does not report your payments to Canada’s major credit bureaus. Many lenders fail to report on-time payments to Equifax or TransUnion, which means you make every payment faithfully and still end up with no credit history at the end of your vehicleloan. You miss the single greatest benefit of taking out a vehicle loan in the first place. Always ask a lender directly whether they report to the bureaus before you sign anything.
The second trap is add-ons. Extended warranties and gap insurance are sometimes bundled into a car or truck loan without being clearly explained. Each addition increases your total loan amount and your monthly payment. The add-on trap is particularly costly for borrowers without credit experience because it can make refinancing or paying off the vehicle loan early much more difficult. Read every line of your loan agreement and ask what each charge is for.
“Is no credit auto financing possible?” Yes, absolutely. But the quality of that car financing varies enormously. Your job is to find a lender who is transparent about what you are signing, reports your payments to the credit bureaus, and does not bury costs inside complicated auto loan structures. Trustworthy lenders exist. Choose carefully.
A third misconception worth addressing is that you should apply to as many lenders as possible to improve your chances. This approach creates more problems than it solves. Focus your energy on one lender who genuinely specialises in financing a car with no credit and who has a track record of working with Canadians in your situation.
Tips for successfully vehicle financing your first car
Getting approved is one part of the equation. Managing the auto loan wisely afterward is the other. Here is how to set yourself up for success from the very beginning.
The practical steps that make the biggest difference:
- Budget honestly. Include not just your monthly payment but also insurance, fuel, and maintenance in your vehicle budget. A payment that looks affordable on paper can feel very different when real ownership costs are added.
- Make a down payment if you can. A larger down payment reduces your auto loan amount, improves your approval odds, and lowers your monthly commitment. Even a modest amount helps.
- Choose a realistic vehicle. A reliable used vehicle that fits your budget is a smarter first purchase than a new car that stretches your finances thin.
- Pay on time, every time. If your lender reports to the credit bureaus, every on-time payment is actively building your credit history. Consistency here pays dividends for every future financial product you apply for.
- Review your auto loan terms carefully. Understand the total cost of borrowing, the repayment period, and any fees before signing. Summit Auto Loans is built around transparency, making this conversation much easier for applicants.
For a deeper look at how to qualify for car financing specifically in Alberta, there is solid guidance available that walks through the process step by step.
My perspective on no credit car financing
I have worked with enough people navigating this process to say with real confidence: the fear around no credit auto financing is almost always bigger than the actual obstacle. What I have seen repeatedly is that people with no credit history are often more financially responsible than their paperwork suggests. They pay rent on time, they manage their expenses carefully, they simply have never used formal credit. The system just has not caught up with that reality yet.
What I have learned is that the lender choice matters far more than most people realise. A lender who reports your payments, offers transparent terms, and treats you like a capable adult rather than a liability can genuinely change your financial trajectory. I have watched clients go from zero credit history to a solid borrowing profile within two years of their first auto loan, simply because they chose the right lender.
The emotional side of this process is real too. Sitting across from someone who seems to be judging your financial past is uncomfortable. What I appreciate about how Summit Auto Loans approaches this is that the process is designed to feel supportive, not interrogative. There is no shame in starting from zero. Everyone does, eventually.
— Harvest
Get started with Summit Auto Loans today
If you are ready to explore your options, Summit Auto Loans makes the process straightforward and welcoming. Designed specifically for Canadians with no or poor credit, the platform offers fast pre-approval based on your income and current situation rather than your credit history. There are no invasive procedures, no overwhelming paperwork stacks, and no judgement about where you are starting from. You can get approved today directly on the Summit Auto Loans website and have a specialist walk you through what fits your budget. Reliable transportation is within reach, and Summit Auto Loans is here to help you get there with confidence.
FAQ
What is no credit auto financing?
No credit auto financing is a type of vehicle loan designed for people with little to no borrowing history. Lenders assess your income and employment stability rather than your credit file.
Is no credit auto financing possible in Canada?
Yes. Specialised lenders across Canada, including Summit Auto Loans, offer auto loans to applicants with no credit by focusing on proof of income and employment rather than credit history.
What documents do I need to apply?
Most lenders require recent pay stubs or bank statements, government-issued identification, proof of residence, and employment verification to process a no credit auto loan application.
Will a no credit auto loan help me build credit?
It can, but only if your lender reports your payments to Equifax or TransUnion. Some lenders do not report on-time payments, which means your credit history does not improve even with consistent payments. Always confirm this before signing.
How much income do I need to qualify?
Lenders typically look for a minimum monthly income of around $1,800, verified through pay stubs or bank statements, though requirements vary by lender and vehicle price.
| Point | Details |
|---|---|
| No credit vs. bad credit | No credit means no borrowing history. Bad credit means negative history. They are treated differently by lenders. |
| Key approval factors | Income level, employment stability, and debt-to-income ratio replace credit history as the main criteria. |
| Credit-building potential | Only vehicle loans that report to Equifax or TransUnion will help you build a credit profile over time. |
| Add-on awareness | Bundled products like gap insurance increase total car loan costs. Always ask what each charge covers before signing. |
| Down payment benefit | Even a modest down payment improves approval chances and reduces monthly payment obligations. |