
A lot of Albertans assume that a steady paycheque is all it takes to drive off a lot with a financed vehicle. The truth is more layered than that. Eligibility for a vehicle loan in Alberta depends on the lender you choose, the car you want, your financial profile, and provincial rules designed to protect you. If your credit isn’t perfect, understanding exactly what lenders look for can be the difference between approval and rejection. This guide breaks it all down clearly.
Key Takeaways
| Point | Details |
|---|---|
| Lenders set vehicle rules | Each lender decides which vehicles and borrowers qualify for a car or truck loan. |
| Alberta laws protect buyers | Provincial regulations require full disclosure and fair contracts for all auto loans. |
| Not all cars are eligible | Vehicles with rebuilt titles or high mileage often don’t qualify for auto financing. |
| Preparation improves approval | Good documentation and choosing the right vehicle help increase your approval chances. |
How vehicle loan eligibility works in Alberta
Vehicle eligibility is simply whether a car and its buyer meet a lender’s standards for a loan. It sounds straightforward, but the criteria vary widely depending on who you’re borrowing from. A bank applies a very different standard than a dealership finance arm.
Car financing eligibility in Canada depends on whether you apply through a dealership or directly with a financial institution, and each one runs its own underwriting process. That process weighs your income, credit history, the vehicle’s age and condition, and the loan-to-value ratio (how much you’re borrowing compared to what the car is actually worth).
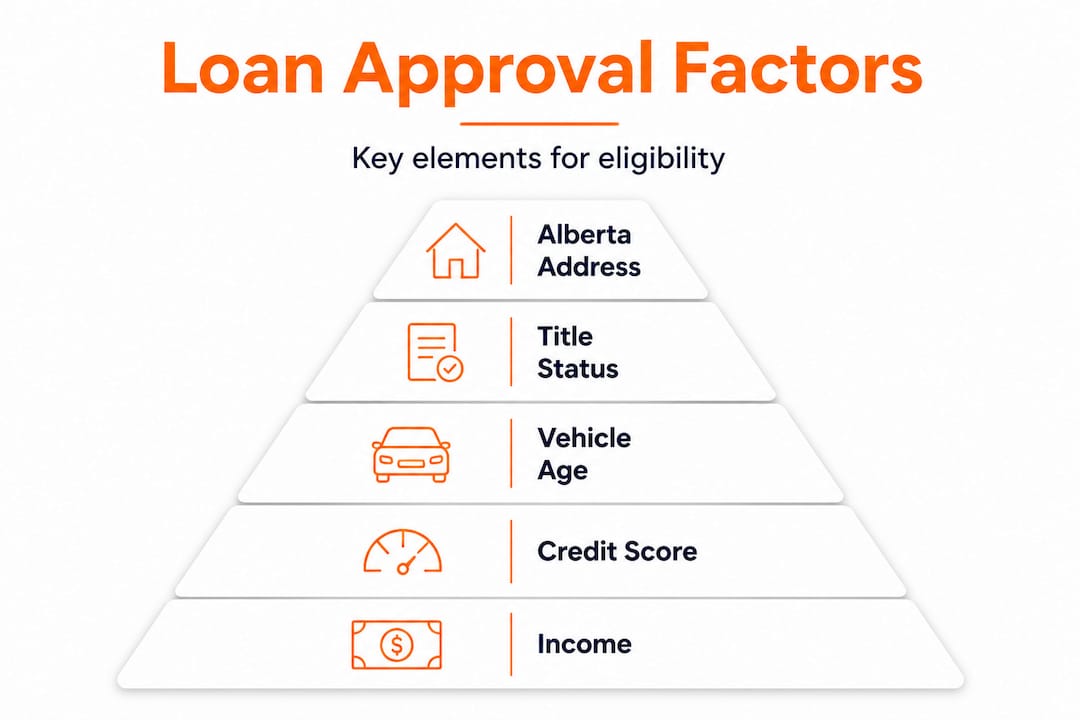
Here’s what lenders typically examine when assessing eligibility:
- Your credit score and payment history
- Your employment status and income stability
- The age, mileage, and condition of the vehicle
- Whether the vehicle has a clean or rebuilt title
- The auto loan amount relative to the vehicle’s market value
Alberta also adds a layer of provincial consumer protection. Lenders and dealerships must be transparent about contract terms and cannot bury costs in the fine print. Before you start shopping, review the Alberta auto loan requirements checklist so you know exactly what to prepare.
Remember: Being eligible isn’t just about whether you want the car—it’s about whether the lender believes both you and the vehicle represent a sound investment of their money.
Who decides if your vehicle is eligible?
The lender sets the rules. But lenders come in several forms, and their standards are not the same.
Banks and credit unions tend to be conservative. They want strong credit scores, usually above 650, stable income, and newer vehicles with low mileage. If your credit has some rough patches, a traditional bank may decline you outright.
Dealerships with their own finance departments or partnerships with alternative lenders often have more flexibility. They work with a network of car financing companies, some of which specialise in qualifying with bad credit. That doesn’t mean anything goes, but it does mean more doors are open.
Here’s a quick comparison to help you see the difference:
| Factor | Bank or credit union | Dealership finance partner |
|---|---|---|
| Credit score requirement | Typically 650+ | Often 500 or lower accepted |
| Income verification | Strict, formal documentation | More flexible options |
| Vehicle age | Usually under 8 years | Up to 10 or 12 years in some cases |
| Approval speed | Several days to a week | Often same day |
| Bad credit options | Very limited | More programmes available |
Pro Tip: Ask the dealership which finance partners they work with. Some specialise in bad credit or no credit situations, and knowing this upfront can save you from a hard credit inquiry at a lender who would decline you anyway.
Whatever route you take, auto loans arranged through a dealership must still meet Alberta’s consumer protection standards. If you’re wondering whether building your credit before applying might be a smarter move, it often is, even a small improvement in your score can shift your interest rate meaningfully.
Provincial rules and disclosure: What Alberta law requires
Eligibility isn’t only about your finances or the car. Alberta’s legislation adds requirements that protect you throughout the vehicle loan process.
Under Alberta’s Cost of Credit Disclosure Regulation, every lender and dealership must provide you with clear, written information before you sign anything. This matters enormously for Albertans with credit challenges, because it prevents lenders from slipping unfair terms into complex contracts.
Alberta’s consumer protection rules require that you shop around and fully understand your car financing contract, including your rights as a borrower.
Here are the disclosure items you are legally entitled to receive:
| Disclosure item | What it means for you |
|---|---|
| Annual interest rate (AIR) | The true yearly cost of your auto loan |
| Total cost of borrowing | Every dollar you’ll pay, including interest |
| Fees and charges | Administration, documentation, or dealer fees |
| Payment schedule | Amount, frequency, and number of payments |
| Prepayment terms | Whether you can pay off early without penalty |
Before you sign any auto loan agreement, follow these steps to protect yourself:
- Read the entire contract, not just the monthly payment amount.
- Compare the annual interest rate across at least two or three lenders.
- Ask specifically about any fees that are not included in the advertised rate.
- Confirm the total amount you will repay over the full loan term.
- Get clarification on early repayment penalties in writing.
For a thorough breakdown of what’s needed before you apply, revisit the car financing requirements in Alberta guide.
Your rights matter: No dealership can legally pressure you into signing without giving you full cost disclosure. If something feels unclear, walk away and ask questions.
Which vehicles usually qualify for auto loans?
Not every vehicle on a lot will qualify for car or truck financing. Lenders assess the car itself as part of their risk calculation, because the vehicle is the collateral for the vehicle loan.
Most standard used and new vehicles qualify when they are under ten years old and have reasonable mileage, generally under 150,000 kilometres. Personal vehicles are the most common, but some lenders will also finance light commercial vehicles like pickup trucks used for a small business.
Lender underwriting determines eligibility for both you and the vehicle, so a great credit profile won’t override a problematic car.
Vehicles that typically qualify:
- New or certified pre-owned vehicles from a dealership
- Used vehicles under ten years old with under 150,000 km
- Light trucks and SUVs in good mechanical condition
- Vehicles with clean title history
Vehicles that commonly don’t qualify:
- Cars with rebuilt or salvage titles
- Vehicles with more than 200,000 km on the odometer
- Out-of-province vehicles that haven’t been properly inspected or registered in Alberta
- Vehicles with significant undisclosed damage or outstanding liens
Pro Tip: Always request the vehicle history report before applying for car financing. A report showing a rebuilt title or an accident history can disqualify the car and cost you a hard credit inquiry.
If you’re searching in a specific city, check out auto loan options in Edmonton or explore Calgary auto financing options to find vehicles that lenders are already comfortable working with.
How lenders assess risk: Factors that impact your approval
Understanding a lender’s thought process gives you a real advantage, especially if your credit isn’t strong. They’re not just checking a box. They’re building a picture of how likely you are to repay the auto loan without defaulting.
Here are the main factors lenders review:
- Credit score and history: Even a score in the low 500s can work with the right lender.
- Monthly income: Lenders want to see that your auto loan payment won’t exceed roughly 15 to 20 percent of your monthly take-home pay.
- Employment stability: Permanent employment is preferred, but many lenders accept self-employed applicants with proper documentation.
- Down payment: A larger down payment reduces the lender’s risk and often improves your rate.
- Vehicle age and mileage: Newer vehicles with lower mileage are lower risk as collateral.
- Debt-to-income ratio: This is how much of your income is already going toward existing debts.
There are bad credit car loan myths worth reading before you apply, because many people underestimate their actual chances of approval.
To improve your odds before applying, consider these steps:
- Gather at least two recent pay stubs or a formal letter of employment
- Have proof of your Alberta address, such as a utility bill
- Save for a down payment of at least $1,000 if possible
- Get a vehicle inspection from a licensed mechanic
- Use an auto loan calculator to estimate what you can realistically afford before you walk into a dealership
Why eligibility rules help more than they hinder
Here’s a perspective that might surprise you: Alberta’s eligibility rules are actually one of the best things working in your favour, even if your credit isn’t perfect.
Many borrowers with low credit scores first encounter eligibility requirements as obstacles. They feel like the system is designed to keep them out. But the opposite is often true. Those rules force lenders to be transparent about costs, prevent dealerships from sneaking fees into contracts, and ensure you’re never handed a car loan you genuinely cannot repay without clear knowledge of the terms.
We’ve seen borrowers come through our process who were frustrated by a previous denial. In nearly every case, the issue wasn’t that they were unqualified. It was that they hadn’t known what to prepare. Once they reviewed the checklist for Alberta vehicle loans, gathered the right documents, and chose an eligible vehicle, the path forward became much clearer.
The uncomfortable truth is that most people who struggle to get approved aren’t financially unworthy. They simply didn’t understand the process well enough to present themselves properly. Eligibility requirements give you a roadmap. Use them.
Find your next eligible vehicle with Summit Auto Loans
At Summit Auto Loans, we connect Albertans to vehicle financing that works for their real situation, whether that means bad credit, no credit, or simply needing a faster and more transparent process than a traditional bank offers. You can calculate your auto loan right now to see what fits your budget, or get approved quickly with our online application that takes just minutes. We also offer trade-in and upgrade services to help simplify the switch to your next vehicle. Find a Summit location near you and let’s get you moving.
Frequently asked questions
Can I get a vehicle loan in Alberta with bad credit?
Yes, many lenders and dealerships in Alberta offer solutions for bad or no credit, though you may face higher interest rates or stricter vehicle requirements based on lender underwriting criteria.
What types of vehicles will lenders not finance?
Lenders typically won’t finance vehicles with rebuilt titles, very high mileage over 200,000 km, or those not yet properly registered in Alberta.
Does the dealership have to tell me all SUV, car or truck loan costs upfront?
Yes, Alberta law requires full disclosure of all costs and terms before you sign, as outlined under AMVIC consumer protection rules.
How can I improve my chances of vehicle loan approval?
Provide accurate proof of income and a stable Alberta address, choose a vehicle with a clean title, and consider saving for a modest down payment to reduce lender risk.


